Pan-India economic intelligenceFriday, October 9, 2026
AI2

Ai2India

Daily Edition

One daily issue tracking AI adoption, markets, hiring, layoffs, real estate, credit and gig-work signals across India.

PublishedOctober 9Daily issue
Nifty 50 (Oct 8 close)22,232−371.25 pts (−1.64%) below 22,250 as oil topped $104 on Strait-of-Hormuz fears; VIX +10%; ~₹10 lakh crore of investor wealth lost
Sensex71,593.24−1,045.46 pts (−1.44%) Oct 8 — the worst session since the RBI-hike selloff; geopolitical risk aversion dominated
USD / INR96.88Rupee fell 13 paise to a provisional 96.88 close on risk aversion amid escalating US-Iran tensions and Brent above $104
Brent Crude≈$104.4Futures +4.2% to $104.41 on Oct 8 over Strait of Hormuz supply-disruption fears; WTI jumped ~5.4% to ~$93
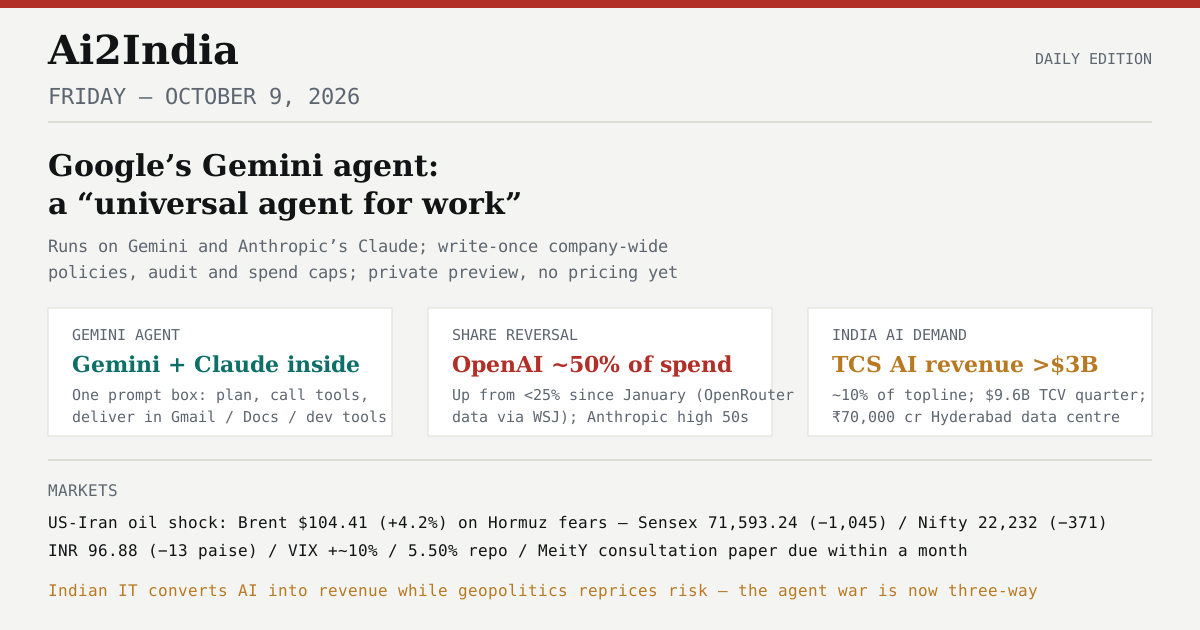
October 9, 2026 signal board: Google Cloud unveils the Gemini agent at Gemini at Work 2026, a universal agent for work that takes goals from a single prompt box, plans, uses tools, connects to company systems and delivers finished work inside Gmail, Docs or development tools, running on both Gemini and Anthropic's Claude models with one company-wide policy applied to every agent, in private preview with no pricing and no general-availability date; the launch makes the enterprise agent platform war three-way, landing the same day WSJ-reported OpenRouter data shows OpenAI's share of developer and enterprise AI spend rising from below 25 percent to nearly 50 percent in 2026 and TCS reporting AI revenue above 3 billion dollars, 10 percent of topline, with a 70,000 crore rupee Hyderabad data-centre project. Same cycle: markets crashed on US-Iran oil fears with the Sensex at 71,593.24 and Nifty at 22,232, Brent above 104 dollars on Strait of Hormuz fears, the rupee at 96.88, and MeitY promising an AI regulation consultation paper within a month
Today’s economic signal board. Full analysis in the Daily Edition.

Lead Analysis

Google launches the Gemini agent, a “universal agent for work” that runs on Claude

One agent plans, calls tools across company systems and delivers finished work in Gmail, Docs and dev tools — private preview, no pricing, and the enterprise agent war just turned three-way

Friday, October 9, 2026: Google Cloud unveiled the Gemini agent Thursday at Gemini at Work 2026 — a single work agent that can answer, act, create and code, running on both Gemini and Anthropic’s Claude models, in private preview with no pricing.

Google Cloud announced the Gemini agent on October 8: one prompt box, and the agent plans, uses tools, connects to company systems and hands back finished work inside Gmail, Docs or development tools. Bloomberg frames it as Alphabet ramping competition with OpenAI, Anthropic and Microsoft for corporate customers. It is the third universal-agent pole in a market Anthropic entered with Claude Cowork/Code and OpenAI is defending with ChatGPT Work, and it arrives with a structural twist: Google opened the agent to Anthropic’s Claude models, so an Indian enterprise can run a multi-model agent under one Google control plane.

The governance design is the enterprise-relevant detail. A policy is written once — “agents may not open documents classified Need to Know” — and Gemini applies it to every agent company-wide instead of per-agent. The agent gets its own mailbox, identity, audit trail and spend caps; coworker agents and industry versions for Financial Services and Legal are in preview, with no price and no general-availability date published. Google’s own framing explains why routing matters now: per-token prices have fallen 98% since 2024 while enterprise AI volume exploded, so “running every simple loop through a premium model quickly breaks corporate budgets.”

The timing is pointed. The same day, WSJ-reported OpenRouter data showed OpenAI’s share of developer and enterprise AI spend climbing from under 25% at the start of 2026 to nearly 50% in September, retaking the OpenRouter weekly spend lead after two and a half years as Anthropic slipped from 75-80% to the high 50s. Anthropic’s IPO roadshow is now reported for the week of November 9 — with its public S-1 still missing from EDGAR and a late-October filing deadline looming — so Google is planting its enterprise flag exactly as the two front-runners wage a pre-IPO share war.

For Indian enterprises the relevance is immediate. Google Workspace and Google Cloud are the default stack for a large share of Indian GCCs, BFSI and mid-market operations, so the Gemini agent plus Claude-inside gives buyers a multi-model agent platform with policy and audit controls that map directly onto the compliance lanes India is now building — MeitY promised Thursday an AI regulation consultation paper within a month (safety, deepfakes, human-first), and company-wide agent policy enforcement is precisely the control India’s binding-lanes proposal anticipates. TCS’s Q2 print the same evening — AI revenue above $3 billion, 10% of topline — shows the demand this platform layer will be sold into.

Macro context arrived as a down-day counterpoint: markets crashed Thursday on US-Iran escalation and Strait-of-Hormuz supply fears — Sensex 71,593.24 (−1,045.46, −1.44%), Nifty 22,232 (−371.25, −1.64%), Brent futures +4.2% to $104.41, rupee to 96.88, VIX up ~10% — with roughly ₹10 lakh crore of investor wealth erased. The AI tape and the macro tape have diverged: platform competition is accelerating while oil reprices risk into the same tightening cycle the RBI started last week.
Read full Daily Edition →
AI-generated illustration for: Google launches the Gemini agent, a “universal agent for work” that runs on Claude
AI-generated illustration. Not a photograph of the events described.

AI Developments Today

Friday, October 9, 2026: Top AI stories with source, India relevance, and enterprise impact. This cycle’s lead: Google’s Gemini agent (Lead Analysis) — a universal work agent running on Gemini and Claude, in private preview with no pricing, making the enterprise agent platform war three-way. Below, the global tape — OpenAI’s OpenRouter share clawback (WSJ), Anthropic’s IPO roadshow moving to the week of November 9 with its public S-1 still pending, TCS’s Q2 showing AI at 10% of topline, and MeitY’s consultation-paper promise.

StoryKey DetailsIndia RelevanceWhat This Means for Indian EnterpriseSource / Date
Google launches the Gemini agent — “universal agent for work”
Runs on Gemini and Claude; private preview, no pricing
Oct 8 (Google Cloud blog; Bloomberg; Reuters; 9to5Google; QZ; beri.net; cellcog; kingy.ai): announced at Gemini at Work 2026 — a single agent that takes goals from one prompt box, plans, uses tools, connects to company systems and delivers finished work in Gmail, Docs or dev tools; runs on Gemini and Anthropic’s Claude models; one company-wide policy (e.g. “agents may not open documents classified Need to Know”) applied to every agent; own mailbox, identity, audit and spend caps; coworker agents undated; Financial Services and Legal industry versions in preview; no price, no GA date; Google: per-token prices down 98% since 2024 while enterprise volume exploded. Directly relevant: Google Workspace/Cloud is the default stack across Indian GCCs, BFSI and mid-market; the agent plus Claude-inside gives a multi-model platform under one policy-and-audit control plane; the governance design (write-once, apply-to-all-agents) maps onto the compliance lanes India is building, including MeitY’s promised consultation paper. For Indian enterprises: (1) evaluate the agent as a Workspace-native route to agentic workflows with built-in policy enforcement; (2) treat the no-pricing private preview as an evaluation window, not a procurement signal; (3) benchmark its routing economics against the value tier (Haiku 5.5/Luna at $0.10/$0.50); (4) use the audit/spend-cap controls to pilot governed agents ahead of MeitY rulemaking. Verified global — Google Cloud; Bloomberg; Reuters; Oct 8, 2026
OpenAI claws share back from Anthropic
OpenRouter data: under 25% to ~50% of developer/AI spend in 2026
Oct 8 (WSJ via Gizmodo; AOL; Kantan News; aiweekly): an OpenRouter-data-based report seen by the WSJ shows OpenAI’s share of developer and enterprise AI spend rose from under 25% at the start of 2026 to nearly 50% in September; OpenAI retook the OpenRouter weekly spend lead after ~2.5 years; Anthropic held 75-80% of combined OpenRouter spend across most of 2024-2025, slipped to the high 50s by mid-August 2026, then OpenAI edged past; WSJ frames the shift as part of a wider price war in coding and productivity workloads. A supplier-durability signal for the Indian enterprise AI stack: the share data tracks the exact workloads Indian GCCs and IT firms buy at scale (coding, productivity, agent pipelines), so contract leverage shifts as OpenAI regains the default position. For Indian enterprises: (1) keep multi-vendor routing rather than lock-in to the current leader; (2) re-run vendor evaluations with the new lead-time data; (3) use the price-war context to negotiate volume terms before Anthropic’s IPO books close; (4) watch whether the clawback reflects price, capability or bundling. Verified global — WSJ via OpenRouter data; Gizmodo; aiweekly; Oct 8, 2026
Anthropic IPO roadshow moves to week of Nov 9; public S-1 still pending
Late-October EDGAR deadline; OpenAI rules out 2026 listing
Oct 5-8 (Bloomberg; Yahoo Finance FInance/Forge; implicator; Motley Fool; kalkine): roadshow reported to start the week of November 9 with a debut before Thanksgiving (Nov 26) and no later than end-2026; Anthropic to host prospective investors at its SF headquarters October 14; the public S-1 still missing from EDGAR — if marketing starts Nov 9 the S-1 must appear by late October, compressing investor-education time; ~$2T valuation reporting stands; Motley Fool: OpenAI has ruled out a 2026 IPO after Altman prioritised safety-confident timing. Indian enterprises time multi-year AI contracts around the repricing moves that pre-IPO windows produce; the S-1 delay and OpenAI’s 2026 exit keep both vendors’ near-term packaging behaviour uncertain into Indian Q3 FY27 planning. For Indian enterprises: (1) put Oct 14 and the late-October EDGAR window on the vendor-risk calendar; (2) re-check discount-unwind and volume terms in Anthropic contracts; (3) expect continued packaging moves (bundles, cache tiers) from both labs through November; (4) keep the Gemini agent launch in sourcing comparisons as a third platform option. Verified global — Bloomberg; Forge; Motley Fool; Oct 5-8, 2026
TCS Q2 FY27: AI revenue tops $3B, ~10% of topline
PAT ₹13,884 cr (+15% YoY); TCV $9.6B; ₹70,000 cr Hyderabad data centre
Oct 8 (TCS press release; CNBC-TV18; ThePrint; Moneycontrol; Rediff; LiveMint): Q2 PAT ₹13,884 crore, +15% YoY (+4% QoQ, ahead of the poll); AI revenue above $3 billion, ~10% of revenue; deal wins $9.6B TCV including a $1.45B mega deal; acquired Porsche’s IT unit MHP; announced a ₹70,000 crore data-centre project in Hyderabad; 10,000 graduates onboarded globally; dividend ₹12/share; analysts debate whether AI revenue is new growth or re-labelled services. The strongest India AI-adoption datapoint of the year: the country’s largest IT firm now books a double-digit share of revenue from AI work, with a data-centre bet that scales domestic AI infrastructure alongside it. For Indian enterprises: (1) read the $9.6B TCV and $1.45B mega deal as demand evidence for AI-led transformation contracts; (2) track whether AI-revenue disclosure is new growth or re-labelling in the Q2 season; (3) note the ₹70,000 cr data-centre pipeline as a capacity signal for AI workloads; (4) benchmark TCS AI pricing against platform alternatives like the Gemini agent. Verified India — TCS; CNBC-TV18; ThePrint; Oct 8, 2026
MeitY promises AI regulation consultation paper within a month
Safety, deepfakes, human-first headline the agenda
Oct 8 (The Hindu; ThePrint; New Indian Express; ETV Bharat; Careerindia; bhaskarenglish): IT minister Vaishnaw said MeitY will publish a regulation-focused AI consultation paper within a month, covering AI safety, deepfakes, user harm and a human-first approach with skilling; unveiled at the New Delhi launch of the World Bank’s World Development Report 2026 ‘The Promise of Artificial Intelligence’ (IndiaAI Mission + MeitY + World Bank); secretary S. Krishnan: the report’s existential risks are laid out ‘far more explicitly’ and ‘maybe some of those times have come’ for regulation. The clearest MeitY execution signal since the Sep 18 ‘maybe the time has come’ reconsideration: a dated rulemaking step Indian enterprises, GCCs and AI vendors must comment on and comply with, on a ~30-day clock. For Indian enterprises: (1) start drafting consultation-paper comment positions on safety, deepfakes and incident handling now; (2) align agent-governance controls (the Gemini agent’s write-once policies are a working template) with anticipated rules; (3) watch the bundled 10,000-GPU procurement (first 5,000 ordered) and model-empanelment roster as public-sector gates. Verified India — The Hindu; ThePrint; New Indian Express; Oct 8, 2026

India AI Ecosystem

Friday, October 9, 2026: Tier 4 platforms, NASSCOM signals, MeitY policy, IT-services AI workforce signals. This cycle’s lead: TCS’s Q2 converts the AI-services narrative into disclosed numbers — AI revenue above $3 billion, ~10% of topline, a $9.6B TCV quarter and a ₹70,000 crore Hyderabad data-centre project while the Gemini agent adds Google as a fourth orchestration-layer competitor. Updated: MeitY’s consultation-paper promise (within a month) and the World Bank WDR 2026 India launch. Carried: IndiaAI round-two pipeline, DPDP workshops, Sarvam, Krutrim, orchestration battleground, IBM-Yotta, NASSCOM Strategic Review.

Platform / SignalUpdateSource / Date
TCS Q2 FY27 AI disclosure (new, lead)AI revenue tops $3 billion, ~10% of topline (Oct 8); PAT ₹13,884 cr (+15% YoY, ahead of polls); TCV $9.6B including a $1.45B mega deal; Porsche IT arm MHP acquired; ₹70,000 crore Hyderabad data-centre project announced; 10,000 graduates onboarded; ₹12/share dividend; analysts split on whether AI revenue is new growth or re-labelling — the Q2 season’s first major test of the AI-services turn.TCS press release; CNBC-TV18; ThePrint; Oct 8, 2026
MeitY consultation paper promise (new)Vaishnaw (Oct 8): regulation-focused AI consultation paper within a month — safety, deepfakes, user harm, human-first, skilling; announced at the World Bank WDR 2026 ‘The Promise of Artificial Intelligence’ India launch (IndiaAI Mission + MeitY + World Bank, adoption-adaptation-advancement theme); Krishnan: ‘maybe some of those times have come’ for regulation; bundled: next 10,000-GPU procurement stage (first 5,000 ordered), 3-4 year indigenous-GPU roadmap, MeitY AI-model empanelment for government use.The Hindu; ThePrint; New Indian Express; pragativadi; Oct 8, 2026
Agent orchestration battleground widens (new)The Gemini agent makes the enterprise-agent fight four-way in India’s IT frame: Google’s universal agent (with Claude inside) now competes directly with the services orchestration stacks — TCS WisdomNext, Infosys Topaz, HCLTech AI Force, Wipro AI360, Tech Mahindra Orion — on delivered-cost and governance; the same day TCS’s AI revenue disclosure validates the demand those layers monetise.Google Cloud; Moneycontrol framing; Oct 8, 2026
IndiaAI foundational-model incentives, round two (carried, watch)ET (Oct 7-8): eight firms expected next — Avataar.ai, Tech Mahindra, Fractal Analytics, Genloop, IntelliHealth, Shodha AI, Zenteiq Aitech Innovations (plus BharatGen) — against ~500 applications and a ₹1,500 crore pool; the government said it has not yet named beneficiaries; round-two announcement remains the week’s pending checkpoint; MeitY common-compute GPU availability “increasingly a challenge” unchanged.Economic Times; Oct 5-8, 2026
DPDP workshop series (carried)“From Readiness to Reality” 16-city series runs New Delhi (opened Oct 7) to January 2027 with MeitY representatives; the compliance-role lane stays live alongside the AI-incident-reporting template.NASSCOM community; Oct 7, 2026
Sarvam AI full-stack pivot + sovereign proposals (carried)Platform hosts third-party and US frontier models (Haiku 5.5/Luna cuts flow through); $234M Series B first close ($1.5B post-money); 2M voice conversations; Saaras V4; Vision 2.1; 30B/105B sovereign proposals under IndiaAI Mission.Moneycontrol; NDTV Profit; Business Standard; Inc42; Sept-Oct 2026
Krutrim cloud-resale pivot (carried, watch)Aggregator read (Tier 3): Krutrim dropped chip plans and pivoted to cloud resale, ~₹300 crore FY26 revenue and a first net profit; watch for company-confirmed filings — watchlist only.university-365 (Tier 3); Oct 1, 2026
Infosys-Columbia enterprise AI centre (carried)AI collaboration and enterprise AI centre launched October 1 beside the 6,000-engineer frontier team and Topaz push.Infosys / feeds (Screener); Oct 1, 2026
Wipro closes Alpha Net Consulting deal (carried)Acquisition of select customer contracts of Alpha Net Consulting LLC completed October 1; customer-contract consolidation as AI-augmented delivery reshapes M&A.Wipro / feeds (Screener); Oct 1, 2026
IBM-Yotta sovereign agentic platform GA (carried)Sovereign Agentic AI Platform (Bengaluru): IBM watsonx Orchestrate on Yotta’s Shakti Cloud with Shakti Studio fine-tuning; security ops, document processing, HR workflows.IBM-Yotta joint release; Sept 29, 2026
NASSCOM Strategic Review 2026 (carried)Outcome-based, risk-sharing revenue models and AI-native M&A markers stand; AI Engineer prints +76% YoY (52 posts per 1,000 professionals); TCS’s Q2 AI disclosure is the first quarterly test of the turn.NASSCOM; Oct 1, 2026
CoRover.ai (BharatGPT) national agentic RFP (carried)Sole winner of the Government of India agentic-AI RFP under MeitY/NeGD (Sept 30); implementation lane and partner-ecosystem hiring stay live.CXO Today; Economic Times; Sept 30, 2026
NFAICF frontier-AI fund (carried)₹20,000 crore National Frontier AI & Compute Fund under consideration as a SEBI Category-I AIF; the 5.50% repo and Thursday’s oil spike raise the cost-of-capital question for the structure.Analytics India Magazine; Inc42; Sept 25-30, 2026

AI Adoption Impact

Friday, October 9, 2026: Enterprise AI adoption data, AI-driven hiring/layoff signals, productivity data, skill demand shifts.

SignalData PointSource / DateTrajectory
Enterprise agent volume forces routing economics (new, lead)Google at Gemini at Work 2026: per-token prices are down 98% since 2024 while enterprise AI volume has exploded; “running every simple loop through a premium model quickly breaks corporate budgets” — the Gemini agent ships with small-model-first routing and company-wide policy controls as the governance answer; coworker agents and Financial Services/Legal editions in preview with no pricing. Concrete signal: the enterprise agent market is moving from single-model assistants to governed multi-model platforms with routing budgets.Google Cloud blog; Bloomberg; Reuters; cellcog; Oct 8, 2026Accelerating
Frontier share reversal documented (new)OpenRouter data (WSJ, Oct 8): OpenAI’s share of developer/enterprise AI spend rose from under 25% (start of 2026) to ~50% (September); OpenAI retook the weekly OpenRouter spend lead after ~2.5 years; Anthropic fell from 75-80% (2024-25) to the high 50s by mid-August; WSJ frames it as a price war in coding and productivity workloads.WSJ via Gizmodo; AOL; Kantan News; aiweekly; Oct 8, 2026Accelerating
AI monetisation hits Indian IT disclosures (new)TCS Q2 FY27: AI revenue above $3B, ~10% of revenue; $9.6B TCV with a $1.45B mega deal; ₹70,000 crore Hyderabad data centre; analysts debate new-growth vs re-labelling — the first disclosed double-digit AI share at a top-5 Indian IT firm.TCS; CNBC-TV18; ThePrint; Moneycontrol; Oct 8, 2026Accelerating
Carried baselinesClaude Haiku 5.5 $0.10/$0.50 (75-90% cut, Oct 7); GPT-6 Luna same band; Mistral ML4 weights Oct 27 ($1.36/$4.18 preview); GLM 5.3 Fast/Chinese catch-up (Reuters); frontier revenue concentration 89% (The Information); September hiring: AI/ML +20% YoY inside a +2% white-collar market (Naukri); workforce-intelligence M&A (SAP-TechWolf); S&P Global productivity-first research; local-agent cost engineering (DGX Spark $4,999); Microsoft DDR sub-24h weaponization; Anthropic Frontier Academy; OpenAI run rate ~$70B; GCC restructuring playbook (up to 30,000 roles at risk, watchlist); NASSCOM 1M AI demand vs ~53% skills gap; Infosys frontier team 6,000; evaluator economy ~$2B (Anthropic-Accenture); GPT-6 Astra $10/$50 and Ultrafast $300/M output; Perplexity Decisions $0.04/M.Aug-Oct 2026Widening

Five Things That Changed

Friday, October 9, 2026: 3 AI items, 2 economy items, each with verified data and source.

SignalData PointReader ImpactStatus
1. Google launches the Gemini agent (Google Cloud blog; Bloomberg; Reuters, Oct 8): a “universal agent for work” unveiled at Gemini at Work 2026 — one prompt box that plans, uses tools, connects to company systems and delivers finished work in Gmail, Docs or dev tools; runs on Gemini and Anthropic’s Claude models; write-once company-wide agent policies; private preview with no pricing or GA date; coworker agents and Financial Services/Legal versions in preview. The enterprise agent platform market becomes three-way (Google vs OpenAI vs Anthropic, with Microsoft) and multi-model: one control plane can now route across Gemini and Claude with policy, audit and spend-cap controls. Start a governed-agent pilot on Workspace if available; benchmark routing economics against the $0.10/$0.50 value tier; use the no-price evaluation window before the platform war settles. Verified global — Google Cloud; Bloomberg; Oct 8, 2026
2. OpenAI claws share back from Anthropic (WSJ via OpenRouter data, Oct 8): OpenAI’s share of developer/enterprise AI spend rose from under 25% at the start of 2026 to nearly 50% in September; it retook the OpenRouter weekly spend lead after ~2.5 years; Anthropic slipped from 75-80% to the high 50s by mid-August; WSJ frames the shift as part of a wider price war. The market-structure fiction of a stable duopoly breaks: share can swing ~25 points in nine months on price, bundling and coding/productivity competition. Keep multi-vendor routing; re-run vendor evaluations with fresh lead-time data; negotiate volume terms before Anthropic’s books close. Verified global — WSJ via OpenRouter; Oct 8, 2026
3. TCS Q2 FY27: AI revenue tops $3B (TCS; CNBC-TV18; ThePrint, Oct 8): PAT ₹13,884 cr (+15% YoY); AI ~10% of topline; TCV $9.6B incl. a $1.45B mega deal; Porsche’s IT arm MHP acquired; ₹70,000 crore Hyderabad data-centre project; 10,000 graduates onboarded; ₹12/share dividend. India’s largest IT firm discloses a double-digit AI revenue share and pairs it with a data-centre buildout — the AI-services monetisation turn moves from narrative to numbers. Watch Q2 season peers (Infosys, Wipro, HCLTech) for comparable AI disclosures; track whether TCS AI revenue is new growth or re-labelling; note the DC capacity signal. Verified India — TCS; CNBC-TV18; Oct 8, 2026
4. Economy: stocks crash on US-Iran oil fears (NDTV; Moneycontrol; Business Standard; The Hindu BusinessLine, Oct 8): Sensex fell 1,045.46 pts (−1.44%) to 71,593.24 and Nifty fell 371.25 pts (−1.64%) to 22,232, with VIX jumping ~10% and investors losing roughly ₹10 lakh crore; Brent futures +4.2% to $104.41 on Strait-of-Hormuz supply-disruption fears; the 2026 Iran war has produced what the IEA calls the largest supply disruption in the history of the global oil market. The worst session since the RBI-hike selloff: geopolitics, not rates, is now the driver, with oil above $104 re-tightening the inflation calculus behind last week’s 5.50% repo hike. Brace for crude-linked volatility into Q2 results season; watch rate-sensitive sectors and FII flows; oil re-tests of $104+ keep the RBI hawkish and rupee under pressure. Verified India — NDTV; Moneycontrol; Business Standard; Oct 8, 2026
5. Economy: rupee falls 13 paise to 96.88; Brent above $104 (The Hindu; CNBC-TV18; HDFC Sky; TradingEconomics, Oct 8): the rupee closed at a provisional 96.88 against the dollar on risk aversion amid escalating geopolitical tensions; Brent futures rose ~4.2% to $104.41 on concerns over crude supplies through the Strait of Hormuz, with WTI up ~5.4% to ~$93; the October 7 RBI hike (5.50%, calibrated tightening) frames the currency and inflation tape. The rupee is back above its post-hike low and crude reprices the same oil shock that justified the tightening cycle; the RBI anchor is being tested on both sides at once. Hedge oil-linked input costs and dollar payables; expect 96.9-97+ prints if Hormuz disruptions persist; the 97 depreciation forecast re-arms. Verified India — The Hindu; CNBC-TV18; Oct 8, 2026

Data Variables Ledger

Friday, October 9, 2026: Key numbers for AI and economy trackers. Updated with this cycle’s verified data points; the agent-platform and AI-revenue rows are new.

VariableCurrent ValuePrior ValueChangeSource / Date
Google Gemini agent (new, lead)Announced Oct 8 at Gemini at Work 2026: universal work agent; runs on Gemini + Anthropic Claude; write-once company-wide policies (e.g. “agents may not open documents classified Need to Know”); own mailbox, identity, audit, spend caps; coworker agents undated; Financial Services/Legal in preview; private preview, no pricing, no GA date; Google: token prices down 98% since 2024 while enterprise volume explodedNo comparable Google work agentEnterprise agent market becomes three-way; multi-model (Gemini + Claude)Google Cloud blog; Bloomberg; Reuters; 9to5Google; beri.net; Oct 8, 2026
OpenAI share of developer/AI spend (new)<25% at start of 2026 → ~50% by September (OpenRouter data via WSJ); weekly OpenRouter spend lead retaken after ~2.5 years; Anthropic 75-80% (2024-25) → high 50s by mid-August 2026Anthropic duopoly lead~25-point swing in nine months; price-war framingWSJ via Gizmodo; AOL; aiweekly; Oct 8, 2026
TCS Q2 FY27 AI revenue (new)AI revenue >$3B, ~10% of topline; PAT ₹13,884 cr (+15% YoY, +4% QoQ); TCV $9.6B incl. $1.45B mega deal; MHP (Porsche IT) acquired; ₹70,000 cr Hyderabad DC; 10,000 grads onboarded; dividend ₹12/shareQ1 FY27: AI ~$1.6B (~8%) run-rate disclosure eraFirst disclosed double-digit AI share at a top-5 Indian IT firmTCS; CNBC-TV18; ThePrint; Moneycontrol; Oct 8, 2026
Sensex71,593.24 (Oct 8 close; −1,045.46, −1.44%)72,638.70 (Oct 7 close)Worst session since the RBI-hike selloff; geopolitical risk dominatesMoneycontrol; NDTV; Business Standard; Oct 8, 2026
Nifty 5022,232 (Oct 8 close; −371.25, −1.64%), below 22,25022,603.70 (Oct 7 close)Broke 22,400/22,250 on oil and Hormuz fears; VIX +~10%Business Standard; Moneycontrol; Oct 8, 2026
USD/INR96.88 (provisional Oct 8 close; −13 paise)96.75 (Oct 7 close area)Weaker on risk aversion, crude >$104 and FII outflowsThe Hindu; CNBC-TV18; HDFC Sky; Oct 8, 2026
Brent Crude≈$104.4 (Brent futures +4.2% to $104.41 Oct 8 on Strait-of-Hormuz disruption fears); WTI ~$93.03 (+5.38%)≈$101.5 (Oct 7)Sharp spike on US-Iran escalation; IEA: largest supply disruption in oil-market history (2026 Iran war)The Hindu BusinessLine; TradingEconomics; HDFC Sky; NBC News; Oct 8, 2026
RBI repo rate (carried)5.50% (hiked +25bp Oct 7, unanimous; stance “calibrated tightening”; first hike since Feb 2023)5.25%+25bp; tightening cycle begunRBI; The Hindu; CNBC-TV18; Oct 7, 2026
Anthropic IPO calendar (updated)Roadshow week of Nov 9 (Bloomberg); SF investor day Oct 14; public S-1 still missing from EDGAR — must appear by late October for a Nov 9 marketing start; debut before Thanksgiving (Nov 26), no later than end-2026; ~$2T valuation reporting; OpenAI ruled out a 2026 IPO“Mid-November target”Dated roadshow + S-1 deadline; OpenAI exits 2026 raceBloomberg; Forge; Yahoo Finance; Motley Fool; Oct 5-8, 2026
MeitY AI regulation consultation paper (new)Promise (Oct 8, Vaishnaw): consultation paper within a month on safety, deepfakes, user harm, human-first, skilling; bundled: next 10,000-GPU procurement stage (first 5,000 ordered), 3-4 yr indigenous-GPU inference roadmap, AI-model empanelment for government use; WDR 2026 ‘The Promise of Artificial Intelligence’ India launchHybrid voluntary-mandatory stance; “too soon to regulate” (Sep 18)Dated rulemaking step; regulation lane converts to executionThe Hindu; ThePrint; New Indian Express; Oct 8, 2026
Claude Haiku 5.5 (carried)$0.10/M in, $0.50/M out (≤100K); $0.50/$2.50 above; cache read $0.01; ~75-90% cheaper than Haiku 4.5; matches GPT-6 LunaHaiku 4.5 bandSmall-model floor halves (Oct 7)anthropic.com; VentureBeat; Oct 7, 2026
Mistral Large 4 “Le Chonk” (carried)Preview $1.36/$4.18; 1.05T MoE, 49B active; open weights dated October 27Weights “end-October”Dated weight-dropmistral.ai; Reuters; Oct 6-7, 2026
IndiaAI foundational-model proposals (carried)~500 applications; ₹1,500 cr pool; eight firms expected in round two (Avataar.ai, Tech Mahindra, Fractal, Genloop, IntelliHealth, Shodha AI, Zenteiq; BharatGen); beneficiaries not yet named; GPU availability “increasingly a challenge”UnchangedAnnouncement still pendingEconomic Times; Oct 5-8, 2026
Naukri JobSpeak September (carried)White-collar +2% YoY; AI/ML +20% YoY (record); IT-services recruitment subduedAugust: index 3,028; AI/ML +31% YoYAI/ML lane outgrows the market ~10xET; ANI; TechGig; Oct 2-3, 2026
US-China trade truce (carried)Extended to Jan 10, 2027; semiconductor export controls unchangedExpiring November 2026Two-month extension standsBloomberg; CNBC; NYT

Verified Layoff Radar

Friday, October 9, 2026: India-confirmed only. AI-driven restructuring flagged separately from general cost cuts. No fresh layoff-radar sweep file this cycle (most recent sweep on file: June 1); no new sweep-derived India item. No new India-confirmed layoff events this cycle; TCS’s Q2 (net hiring, 10,000 graduates onboarded, AI workforce expanding) is the counter-signal, and the oil spike plus 5.50% repo frame Q3 cost commentary without changing any disclosed headcount plan. Carried rows stand with the same source discipline — global totals are never converted into India numbers.

CompanyIndia ImpactDriverSource / DateStatus
Top-5 Indian IT firms (carried)FY26 combined net reduction ~7,000 vs +12,700 added in FY25 (TeamLease via TOI, Oct 1); campus hiring at a two-decade low; bench utilisation the leading indicator (The Hindu); September Naukri confirms AI/ML-led mix (+20% YoY) inside a +2% white-collar market; TCS’s Q2 (Oct 8) shows the hiring-side counterpoint — net positive headcount and 10,000 graduates onboarded.AI-augmented delivery + precision hiring; structural shift, not cyclicalTimes of India; TeamLease; Economic Times; The Hindu; TCS; Oct 1-8, 2026Verified India — FY26 aggregate
Indian IT bench compression (carried, watchlist)Wipro changed how long some employees can remain without a billable project; utilisation policy tightening across the sector as AI-augmented delivery and muted demand compress the bench-as-buffer model. Not a layoff event; the leading indicator into Q2 FY27 disclosures (TCS’s print suggests demand is firmer than feared).AI-augmented delivery + muted demand (utilisation policy)The Hindu; Oct 3, 2026Verified India — Utilisation signal
Apple (carried, watchlist)Restructuring under CEO John Ternus with engineering program managers targeted (reported Oct 4-5); no India split disclosed; Indian listings continue for manufacturing-intelligence, agentic systems and AI data-platform roles.AI/automation + cost control; no causal breakdownLatestLY (Tier 3); NDTV; Oct 4-5, 2026Watchlist — global, no India split
Global info/finance job losses (carried, aggregate)EY: information and financial industries lost 200,000+ jobs since start of 2026; region-agnostic, no India component — do not convert. Carried aggregates (SkillSyncer 225,122; TrueUp 190,077; layoffs.fyi ~130,000; India Today ~1.76 lakh Jan-Sep 2026) stand.Cost discipline + AI integrationEY via teleSUR; SkillSyncer; TrueUp; layoffs.fyi; Oct 4, 2026Verified global — Aggregate
GCC role-reduction estimates (carried, watchlist)Moneycontrol via Business Today: up to 30,000 GCC roles could be eliminated; Zinnov: 55% of the GCC portfolio carries AI-displacement exposure; counterweight: TCS absorbs Best Buy’s Bengaluru GCC (~450) into an AI Capability Centre and now reports AI revenue >$3B. Projection with no company-disclosed India split — watchlist only.AI reallocation + global restructuring pass-throughMoneycontrol via Business Today; Zinnov; HinduBusinessLine; Sept 30-Oct 8, 2026Watchlist — Projection, no India split
TCS-Best Buy (carried, hiring-side)TCS absorbs ~450 Best Buy India GCC employees (Bengaluru) into an AI-native Capability Centre; Q2 adds 10,000 graduates onboarded globally — a hiring-side absorption, not a layoff.GCC-to-services consolidation (AI-native capture)HinduBusinessLine; Deccan Herald; TCS; Oct 1-8, 2026Verified India — Absorption
Oracle (carried)Around 3,000 Indian employees potentially affected; FY26 restructuring projection ~$2.8B with an additional ~$700M charge disclosed; People Matters estimates India absorbed over half of the 21,000 FY26 cuts. India split company-undisclosed.AI/cloud-infrastructure spend redirectTimes Now; Fortune India; People Matters; Bloomberg; Sept 2026Reported India — company-undisclosed
Microsoft consumer Copilot retreat (carried, watchlist)Copilot consolidated into a corporate-only product; consumer line folded in. No India workforce numbers; $20.5B India commitment and Hyderabad region continue.AI strategy consolidation; not a layoff eventBloomberg; Windows Central; Sept 25-27, 2026Watchlist — No India split
Wipro (carried)AI productivity = 20,000-employee capacity, redeployed internally; NO layoffs; bench policy tightening (The Hindu); closed Alpha Net Consulting customer-contracts acquisition Oct 1. Exited Nifty 50 effective Sept 30.AI-skilled workforce build; redeployment-firstIndia Today; Wipro PR; The Hindu; Oct 2026Verified India — Redeployment
Infosys (carried)20K freshers FY27; headcount −532 QoQ; AI revenue $1.6B (~8%); 80,000-100,000 roles being reskilled; 6,000-engineer frontier team; outcome-based billing; Columbia enterprise-AI centre (Oct 1).AI revenue scale-up; reskill-first workforce shiftInfosys Q1; Reuters; HBL; Business Today; Sept-Oct 2026Verified India — Reskill-first
TCS (carried, updated)Q2 FY27 (Oct 8): PAT ₹13,884 cr (+15% YoY); AI revenue >$3B (~10% of topline); 10,000 graduates onboarded globally; Q1 net +2,356; FDE target 5,900-8,900 FY27; Best Buy AICC adds ~450 AI-native roles in Bengaluru; ₹70,000 cr Hyderabad DC announced.Hiring (AI/ML expanding); campus intake lowerTCS records; CNBC-TV18; ThePrint; Oct 8, 2026Verified India — Net hiring
Cognizant (carried)US PERM filings suspended amid fraud probe; 15,000 Frontier workforce target; ~30% AI-generated code claim (50% target); 25,000 freshers 2025, to exceed 2026.Visa-programme probe; AI-augmented outputEconomic Times; Defense World; Sept 2026Verified India — Visa/probe + output
Meta (carried, global)Project Organization Transformation: ~60% team reduction planned via AI-native teams; May wave partially executed, November wave halted May 19. India split not disclosed.AI-native org design (partial, paused)The Pragmatic Engineer; LA Times; Semafor; Sept-Oct 2026Verified global — no India split
Uber (carried, watchlist)~3,300-role corporate reduction reported early September; no India split disclosed.Restructuring; AI reallocation citedBusiness Standard; TechGig; Sept 11, 2026Watchlist — No India split
Adidas India Tech Hub (carried)Over 350 roles affected at Gurugram India Tech Hub, ~20% of ~700-strong workforce; restructuring runs through December 15. Count variance unresolved.Technology restructuring (AI angle unconfirmed)Economic Times; India Today; Sept 16-17, 2026Reported India — count variance
IIT placement sanctions (carried, hiring-side)IITs stop cooperating with 22 companies for two placement seasons after 150+ unhonoured 2026 offers; hiring-market trust sanction at the top of the campus funnel; not a layoff event.Unhonoured offers amid weak fresher demandindia.com / ET reports; Sept 24-26, 2026Verified India — Hiring sanction
AI-linked losses (Nomura, carried)32,921 vs 83,100 AI hires (2023-Aug 2026), ~2.5:1; CEA flags largest absolute AI impactAI displacement + reskilling churnBusiness Standard; NDTV Profit; Aug-Sep 2026Verified signal — Estimate
OpenAI safety-governance churn (carried, watchlist)Safety transparency lead David Robinson exits; at least six senior safety figures in ~2 years; three safety researchers fired days earlier. Leadership churn — no India workforce numbers.Safety-governance restructuring (leadership)aiweekly (spokesperson); Oct 2, 2026Watchlist — Leadership, no India split

Hiring Demand Watch

Friday, October 9, 2026: AI/ML/data roles vs general IT focus. New this cycle: the Gemini agent creates a named agent-platform engineering lane — agents with policy/audit/spend controls need platform engineers, agent-governance architects and multi-model routing teams; TCS’s Q2 (10,000 graduates onboarded, AI workforce expanding) is the hiring-side counterweight to the structural IT reduction story; the MeitY consultation-paper promise opens a scored compliance-role lane. Carried lanes stand.

SegmentSignalData PointSource / Date
Agent-platform and agent-governance engineering (new, lead)Gemini agent + Claude-insideA universal work agent with write-once company policies, audit trails, spend caps and multi-model routing creates a named role family: agent-platform engineers, agent-governance architects, policy-encoding specialists, multi-model routing and cost-tracking leads; the same controls the MeitY consultation paper will likely probe; pairs with the existing model-routing lane from Haiku 5.5/Luna.Google Cloud; Bloomberg; Oct 8, 2026
AI-monetisation hiring at Indian IT (new, updated)TCS Q2 FY27TCS onboarded 10,000 graduates globally in Q2; AI revenue >$3B (~10% of topline) with a $9.6B TCV quarter — AI delivery, data-centre operations and agent-platform roles expand inside India’s largest IT firm; the $1.45B mega deal adds transformation-delivery teams.TCS; CNBC-TV18; Moneycontrol; Oct 8, 2026
AI-compliance and comment-drafting roles (new)MeitY consultation paperMeitY will publish a consultation paper within a month (safety, deepfakes, human-first) — compliance teams, public-comment drafters, AI-safety and incident-reporting officers become a scored lane for Indian enterprises, GCCs and vendors responding to the rulemaking window.The Hindu; ThePrint; Oct 8, 2026
AI/ML hiring vs white-collar market (carried)Naukri JobSpeak SeptemberWhite-collar hiring +2% YoY; AI/ML roles +20% YoY (record); automotive and GCC strong in southern cities; IT-services recruitment subdued: the AI/ML lane outgrows the overall market roughly 10x.ET; ANI; TechGig; Oct 2-3, 2026
Indigenous model-building roles (carried)IndiaAI round-two incentives~500 proposals; eight firms expected next (Avataar.ai, Tech Mahindra, Fractal Analytics, Genloop, IntelliHealth, Shodha AI, Zenteiq, BharatGen) — model-training, fine-tuning and inference-engineering teams across at least eight organisations; beneficiaries not yet named.Economic Times; Oct 5-8, 2026
Model-validation and safety-engineering roles (carried)NYC 10-bill package + guardrail-refusal tapeMandatory third-party validation, human kill switches, 24-hour incident reporting and whistleblower incentives name a global role family: independent AI model validators, kill-switch/system auditors, incident-reporting officers, AI-liability compliance leads.amNY; Gothamist; Fox News; Oct 5-6, 2026
Indian IT structural demand shift (carried)Times of India / TeamLease + Sept NaukriAI, cloud and cybersecurity skills keep moving (voluntary attrition 13-14%); legacy positions face redundancy; top-5 firms net −7,000 FY26 vs +12,700 FY25; TCS Q2 shows the AI-side hiring offset.Times of India; TeamLease; ET; TCS; Oct 1-8, 2026
Frontier Deployed Engineer credentialing (carried)Anthropic Claude Frontier Academy$100M for 10,000 FDEs by end-2027; graded practical exam plus 12-week project residency; first grads early 2027; SF/NY/London cohorts; watch Bengaluru/Mumbai expansion; IPO window keeps delivery capacity central.Anthropic (Tier 1); Oct 2-4, 2026
AI-native GCC capture (carried)TCS-Best Buy AICC~450 Bengaluru staff absorbed into an AI-native Capability Centre with retail-domain AI focus — services-side role capture countering GCC-displacement projections.HinduBusinessLine; Deccan Herald; Oct 1-2, 2026
Coding-agent economics (carried, updated)Grok 4.7 + Sol + Claude Code + Gemini agentGrok 4.7 at $2/$6 (DeepSWE ~71%), GPT-6.1 Sol at $2/$10, Claude Code $2.5B+ run-rate; Haiku 5.5 gives coding pipelines a sub-dollar small-model step; the Gemini agent adds a Workspace-native coding route — multi-model benchmark and cost-engineering teams stay a named skill set.xAI; OpenAI; Mistral; Anthropic; Google; Sept-Oct 2026
DPDP compliance and data-governance roles (carried)NASSCOM × MeitY workshop series16-city implementation workshops opened Oct 7 (New Delhi) through Jan 2027: data-governance officers, DPDP implementation leads, privacy engineers for AI systems.NASSCOM community; Oct 7, 2026
Government agentic-platform implementation (carried)BharatGPT national RFP awardSingle-vendor MeitY/NeGD agentic platform creates a public-sector lane: agent-platform engineers, Indian-language AI specialists, government-workflow developers, compliance roles.CXO Today; ET; Sept 30, 2026
Results-season general-IT hiring tape (carried, updated)Q2 FY27 + 5.50% repo + oil spikeTCS’s $9.6B TCV and +15% profit beat improve the demand read, but the repo at 5.50% and Brent above $104 raise input and capital costs into peers’ Q2 prints (Infosys, Wipro, HCLTech this month) — general-IT lateral hiring stays soft; AI roles the exception.TCS; Business Today; ET; Oct 1-9, 2026
AI job demand (carried)Seven-figure demand windowNASSCOM 2026: AI demand crossing 1M roles; ~53% skills gap; Quess: ~920,000 AI professionals vs ~900,000 gap; TeamLease: 20 lakh upskilled but only ~3 lakh with advanced AI skills (Tier 3).FPJ/ANI; ET; Aug-Oct 2026

Real Estate Pulse

Friday, October 9, 2026: GCC and AI company office moves. New this cycle: TCS’s ₹70,000 crore Hyderabad data-centre project — the largest single AI-infrastructure space signal of the quarter. Everything else carried.

Company / ProjectLocationDetailStatus
TCS Hyderabad data-centre project (new, lead)HyderabadTCS announced a ₹70,000 crore data-centre project in Hyderabad alongside its Q2 FY27 results (Oct 8) — the largest single AI-infrastructure commitment in the current quarterly tape, scaling domestic capacity for the AI workloads behind its >$3B AI revenue line; a supply-side answer to the IndiaAI common-compute GPU constraint debate.Verified India — TCS; CNBC-TV18; Oct 8, 2026
TCS-Best Buy AICC transition (carried)BengaluruBest Buy’s India GCC (BBY Services India LLP, ~450 staff) transfers to TCS under a multi-year agreement and reopens as an AI-native Capability Centre — a reuse-and-transform play on existing GCC real estate rather than a new lease or closure.Verified India — Oct 1-2, 2026
Microsoft 4th India cloud region (carried)HyderabadLaunched Sept 21 under the $20.5B India commitment; three availability zones; zero-water cooling; AI-workload focus; named early adopters include Adani Group, Bajaj Finserv, HDFC Bank and PB Pay.Verified India — Sept 21, 2026
Shillong Tech Park-II (carried)ShillongLargest IT-space boost in the city: StaffFlex LLP (UK BPM), Shamrock AI expansion and Alorica’s largest single commitment, plus an AI Centre of Excellence under the IndiaAI Mission.Verified India — Highland Post; Sept 24, 2026
OpenAI + Anthropic Singapore expansion (carried, global)SingaporeOpenAI in talks to lease ~100,000 sq ft at Shaw Tower; Anthropic opens Singapore office in October, joining Tokyo, Bengaluru, Seoul, Sydney; Anthropic’s Bengaluru presence is the India node of the same Asia network ahead of its Nov 9 roadshow week.Verified global — FT; Sept 20, 2026
GCC space demand (carried)Top 7 citiesGCCs leased 19.2M sq ft in H1 2026 (45% of gross leasing; overall absorption 45.5M record, ANAROCK); Anarock sees GCC expansion adding 8-12M sq ft; Zinnov-NASSCOM FY2026: 2,117 GCCs / 2.36M professionals; TCS’s Hyderabad DC adds AI-infrastructure demand to the office tape.Verified India — ANAROCK; Zinnov; Sept 2026
US-India AI corridor infrastructure push (carried)US-India corridor“Powering the AI Economy” roundtable (Sept 23) put data-centre investment, power and grid readiness on the bilateral agenda; the NFAICF deliberation (₹20,000 cr structure) adds state-anchor capital; the 5.50% repo and $104 oil raise the discount rate on that capex.Verified India — Sept 23-30, 2026
Adidas India Tech Hub (watch, carried)GurugramRestructuring through Dec 15; over 350 roles reportedly affected; reduced tech-hub headcount may free lease space or delay near-term expansion. Count variance unresolved.Watch — ET; India Today; Sept 16-17, 2026
Oracle India GEC footprint (watch, carried)Bengaluru / HyderabadReported ~3,000 employees potentially affected; additional ~$700M restructuring charge disclosed mid-September; GCC absorption supports replacement demand.Watch — Times Now; Startup Fortune; Sept 16-28, 2026
IndiaAI CoE Bhubaneswar (carried)Bhubaneswar, OdishaBlue Cloud Softech Industry Partner for AI Centre of Excellence; MeitY approval; ₹4 cr investmentVerified India — Business Standard; Sept 15, 2026
HCLTech Odisha AI DC + Tech Hub (carried)Bhubaneswar$1.48B AI DC with Sarvam; 5,000-seat hub; 6,000 jobsVerified India — Reuters; Jul 2026
Hyderabad GCC expansion (carried)HyderabadAnarock: GCC expansion may add 8-12M sq ft office demand; GCC leasing grew 1.9M (2021) to 4.5M (2025); 3.05M sq ft GCC absorption in H1 2026Verified India — Anarock; Sept 2026

Market Signals

Friday, October 9, 2026: Brief context only — Sensex, Nifty, INR, crude as 4 ticker cards, with one direct AI-investment angle worth noting. Markets crashed on October 8 as US-Iran escalation and Strait-of-Hormuz supply fears sent Brent above $104 (Sensex 71,593.24, −1.44%; Nifty 22,232, −1.64%), with VIX up ~10% and roughly ₹10 lakh crore of investor wealth erased.

Nifty 5022,232Oct 8 close; −371.25 (−1.64%); below 22,250 as oil topped $104; VIX +~10%
Sensex71,593.24Oct 8 close; −1,045.46 (−1.44%); worst session since the RBI-hike selloff; geopolitical risk aversion
USD/INR96.88Provisional Oct 8 close; −13 paise on risk aversion, Brent >$104 and FII outflows; RBI anchor tested
Brent Crude≈$104.4Futures +4.2% to $104.41 on Strait-of-Hormuz disruption fears; WTI ~$93 (+5.4%); IEA: largest supply disruption ever

Market note: Thursday’s session was a geopolitics-driven rout, not a rates story — Brent jumped ~4.2% to $104.41 on US-Iran escalation and Strait-of-Hormuz supply-disruption fears (the 2026 Iran war has already produced what the IEA calls the largest supply disruption in the history of the global oil market), taking the Sensex down 1,045.46 points to 71,593.24 and Nifty down 371.25 to 22,232 with VIX up ~10% and roughly ₹10 lakh crore of investor wealth erased. The rupee fell 13 paise to a provisional 96.88 close on risk aversion. The 5.50% repo (hiked Oct 7, calibrated tightening) frames the inflation tape: oil above $104 re-tightens the very pressure the RBI just hiked against.

The AI-investment angle is two-sided today. On the demand side, TCS reported AI revenue above $3 billion (~10% of topline), a $9.6B TCV quarter with a $1.45B mega deal, and a ₹70,000 crore Hyderabad data-centre project — India’s largest IT firm is converting AI adoption into disclosed revenue and capex even as the market sells off. On the supply side, the Gemini agent launch and the OpenRouter share data show the enterprise-agent platform war accelerating globally, which raises the competitive stakes for Indian orchestration stacks (WisdomNext, Topaz, AI Force, AI360). The macro headwinds — 5.50% repo, $104 oil, a 96.88 rupee — raise the discount rate on that AI capex, but the demand evidence from TCS is the strongest quarterly print the AI-services thesis has produced.

Forecast Tracker Updates

Friday, October 9, 2026: The enterprise-agent-platform forecast strengthens into a named three-way race — the Gemini agent (running on Gemini and Claude) joins OpenAI and Anthropic with Microsoft in the wings; the AI-services-demand forecast gains its strongest quarterly evidence (TCS AI >$3B, 10% of topline); the Anthropic IPO forecast gains a dated roadshow (week of Nov 9) and a S-1 deadline (late October) while OpenAI exits the 2026 race; the India-governance forecast strengthens with a dated consultation-paper promise; the INR forecast re-arms toward 97 as Brent returns above $104.

ForecastStatusConfidenceLatest Evidence (Oct 9)
Enterprise agent platforms consolidate around 2-3 universal agents (NEW — named race)Active — three-way raceHighOct 9: Google’s Gemini agent (Gemini at Work, Oct 8) runs on Gemini and Claude with write-once company policies, audit and spend caps, private preview, no pricing; OpenAI (ChatGPT Work) holds ~50% of OpenRouter spend; Anthropic (Cowork/Code) preps a Nov 9 roadshow; Microsoft Autopilot in the wings. Testable: GA dates and pricing; enterprise take-up in Indian GCC pipelines by Q1 FY27; whether services orchestration stacks (WisdomNext, Topaz, AI Force, AI360) absorb or compete with the platform agents.
Frontier enterprise pricing splits into tiered variance (CARRIED — holding)Active — small-model floor at $0.10/$0.50HighOct 9: Haiku 5.5 $0.10/$0.50 and Luna same band hold; premium band ($2/$10 Sol; $4/$20 Opus; $1.36/$4.18 ML4 preview) sits 5-40x above the floor; Google’s routing rationale (token prices down 98% since 2024, volume exploded) confirms small-model-first as the default. Testable: enterprise take-up of small-model-first routing; floor moves at the ML4 weight drop (Oct 27) and the IPO window.
Anthropic IPO becomes the largest ever (UPDATED — dated roadshow)On track — roadshow week of Nov 9HighOct 9: Bloomberg: roadshow week of Nov 9, SF investor day Oct 14, debut before Thanksgiving, no later than end-2026; public S-1 still missing from EDGAR (late-October filing deadline for a Nov 9 start); ~$2T reporting; OpenAI ruled out a 2026 IPO. OpenRouter share data (OpenAI ~50% Sept) is the key pricing-stakes input. Testable: S-1 public date; pricing terms; first trade date.
AI services demand expands the IT wallet (STRENGTHENED)On track — TCS AI >$3BHighOct 9: TCS Q2: AI revenue >$3B (~10% of topline), PAT ₹13,884 cr (+15% YoY), TCV $9.6B incl. $1.45B mega deal, ₹70,000 cr Hyderabad DC — the strongest disclosed evidence yet that AI converts into Indian IT revenue and capex. Testable: peer Q2 AI disclosures (Infosys, Wipro, HCLTech); whether AI revenue is new growth or re-labelling; October Naukri prints.
India AI governance hardens into mandatory rules for critical sectors (STRENGTHENED)Active — dated consultation paperMediumOct 9: Vaishnaw (Oct 8): regulation-focused consultation paper within a month — safety, deepfakes, user harm, human-first, skilling (WDR 2026 India launch); bundled 10,000-GPU procurement (first 5,000 ordered), indigenous-GPU roadmap, model empanelment; the Gemini agent’s write-once policy controls are a working template for the agent-governance lane. Testable: paper’s publication (~30 days); BFSI RFP compliance clauses; public-sector model empanelment roster.
INR depreciates to 97+ on crude >$85 (RE-ARMED)Active — crude $104, rupee 96.88MediumOct 9: rupee closed at provisional 96.88 (−13 paise) on risk aversion; Brent +4.2% to $104.41 on Hormuz fears (IEA: largest supply disruption in oil-market history); FII outflows continue; 5.50% repo and $104 oil re-tighten the inflation tape. Testable: prints above 97 this month; Hormuz disruption persistence; RBI anchor behaviour through the tightening cycle.
Repo cycle: first hike since February 2023 (CARRIED — realised)Realised — 5.50%, calibrated tighteningHighOct 9: hike (Oct 7) stands; oil above $104 re-tightens the inflation pressure behind it. Testable: next review’s move; AI-capex-cost maths across IndiaAI Mission, GCC expansion and data-centre buildouts (TCS’s ₹70,000 cr Hyderabad DC is the new reference point).
Open-weight frontier reasserts itself outside the US–China axis (CARRIED)Active — weights Oct 27HighOct 9: Mistral ML4 weights dated Oct 27 (Reuters) with the Gemini agent’s Claude-inside routing adding an open-economics counterweight; Chinese catch-up analysis (GLM 5.3 Fast) stands. Testable: weights ship Oct 27; Indian sovereign-cloud and GCC adoption of self-hosted weights by Q1 FY27.
AI hiring share of IT vacancies >15% by H2 FY27 (CARRIED)On track — record September printHighOct 9: Naukri September (AI/ML +20% YoY, record) stands; TCS onboarded 10,000 graduates with AI >10% of topline; agent-platform/governance lanes add named AI role families. Testable: Naukri October prints; Q2 AI-revenue disclosures; IndiaAI round-two hiring.
IndiaAI Mission compute becomes a PPP-served market (CARRIED — round-two pending)On track — announcement pendingMediumOct 9: round-two beneficiaries still not named (govt confirmed no announcement yet); MeitY’s 10,000-GPU procurement stage (first 5,000 ordered) converts part of the lane to direct government buying; NFAICF ₹20,000 cr AIF reporting stands; 5.50% repo and $104 oil lift the cost of capital. Falsifier: PPP and NFAICF stall past Q1 2027.
Agent governance becomes a hard enterprise control (STRENGTHENED)Statutory prototype + product templateHighOct 9: NYC kill-switch/24-hour reporting provisions and India’s binding-lanes proposal stand; the Gemini agent ships write-once company-wide policies, audit trails and spend caps as the productised control the regulation lane points at; MeitY’s consultation-paper promise (within a month) adds the local clock. Testable: Indian agent-approval workflows and contract clauses by Q1 2027.
Independent AI evaluation becomes a named enterprise spend category (CARRIED)Statutory lane formsHighOct 9: NYC mandatory third-party validation, IndiaAI Safety Institute testing lane and the $2B Anthropic-Accenture pact stand; the three-way agent-platform race adds platform-evaluation as a distinct testable sub-category. Testable: model/platform-audit spend lines in Indian budgets by FY27.
Custom inference and caching reshape the API cost curve (CARRIED)On track — cache floor at a pennyMediumOct 9: Haiku 5.5 cache reads $0.01 and Luna batch/flex at 50% stand; Google’s 98%-price-decline framing and Gemini agent routing confirm the trajectory. Testable: cache-tier and routing adoption in Indian workloads by Q1 FY27.
Nifty IT outperforms Nifty 50 in FY27 (CARRIED — mixed tape)Live test — geopolitics tapeMed-LowOct 9: Thursday’s crash was oil-led and broad; TCS’s beat ($9.6B TCV, AI >$3B) is the fundamental counterweight; peers’ Q2 prints and the $104-oil tape set the next tests. Testable: Q2 margins and TCVs; index gap at quarter-end.
US enters an AI enforcement era (CARRIED)AcceleratingHighOct 9: the 10-bill package, FTC probe and guardrail-refusal tape stand; the OpenRouter share data shows competition, not just regulation, reshaping the market. Testable: bill passage and legal challenges through Q2 2027; MeitY alignment.

Source Notes

Friday, October 9, 2026: Tier 1 = filings/press releases; Tier 2 = named-source business publications; Tier 3 = social/forums and unnamed-source reporting (watchlist only).

#SourceDateTierUsed In
1cloud.google.com/blog (Oct 8: ‘Welcome to Gemini at Work 2026’ — Gemini agent, write-once policies, 98% token-price decline, routing economics); blog.google (Oct 8); bloomberg.com (Oct 8: ‘Google Launches Universal Gemini AI Agent for Workplace’); reuters.com via 1027wbow.com (Oct 8: Google Cloud introduces the Gemini agent); 9to5google.com (Oct 8); qz.com (Oct 8); beri.net (Oct 8: no price, no GA date, agent mailbox/identity/audit/spend caps); kingy.ai and cellcog.ai (Oct 8: private preview, Claude-model access, Financial Services/Legal previews)2026-10-08Tier 1/2Lead; AI Developments; Ecosystem; Adoption; Five Things; Data; Hiring; Forecasts
2WSJ-reported OpenRouter data via gizmodo.com (Oct 8: OpenAI <25% → ~50% share in 2026); aol.com (Oct 8: same figures); kantan.news (Oct 8: coding/productivity doubling); aiweekly.co (Oct 8: OpenAI retakes OpenRouter weekly spend lead after 2.5 years; Anthropic 75-80% → high 50s by mid-August)2026-10-08Tier 2Lead (context); AI Developments; Adoption; Five Things; Data; Forecasts
3tcs.com press release (Oct 8: Q2 FY27 results); cnbctv18.com (Oct 8: profit beats estimates, AI revenue tops $3B, deal wins $9.6B); theprint.in (Oct 8: net profit +15% to ₹13,884 cr, AI 10% of topline); moneycontrol.com (Oct 8: $1.45B mega deal, MHP, ₹70,000 cr Hyderabad DC, 10,000 graduates); livemint.com (Oct 8: ₹12 dividend); rediff.com (Oct 8: revenue +11%)2026-10-08Tier 1/2AI Developments; Ecosystem; Adoption; Five Things; Lead (context); Data; Layoff Radar; Hiring; Real Estate; Market Note; Forecasts
4thehindu.com (Oct 8: consultation paper in a month, safety/deepfakes/human-first); theprint.in (Oct 8: four elements of safety incl. human-first and skilling); newindianexpress.com (Oct 8: user harm focus); etvbharat.com; bhaskarenglish.in; careerindia.com (Oct 8: MeitY within a month); pragativadi.com (Oct 8: WDR 2026 AI India launch, IndiaAI Mission + MeitY + World Bank, adoption-adaptation-advancement)2026-10-08Tier 2AI Developments; Ecosystem; Five Things (context); Data; Hiring; Forecasts
5bloomberg.com via felloai.com and implicator.ai (Oct 5-8: roadshow week of Nov 9, SF investor day Oct 14, debut before Thanksgiving); finance.yahoo.com and forkast.news (Oct 5-6: public S-1 missing from EDGAR, late-October deadline for Nov 9 marketing start); motleyfool.com (Oct 6: OpenAI rules out 2026 IPO); kalkine.com.au (Oct 8: mechanics of confidential filing, Nov 3 vote); forgeglobal.com (Oct: mid-October earliest marketing)2026-10-05/08Tier 2AI Developments; Lead (context); Data; Forecasts
6moneycontrol.com (Oct 8: Nifty below 22,250; Sensex −1,045.46 to 71,593.24; Nifty −371.25 to ~22,231-22,232); ndtv.com (Oct 8: ₹10 lakh crore investor-wealth loss; VIX); business-standard.com (Oct 8: stock market close, oil tops $104, VIX +10%, Nifty ends at 22,232); thehindubusinessline.com (Oct 8: session low 71,617.57; market live)2026-10-08Tier 2Market Strip; Market Signals; Five Things; Data; Forecasts
7thehindu.com (Oct 8: rupee falls 13 paise to 96.88 provisional); cnbctv18.com (Oct 8: rupee 96.88); hdfcsky.com (Oct 8: rupee 96.88, Brent above $104); thehindubusinessline.com (Oct 8: Brent +4.2% to $104.41 on Strait-of-Hormuz concerns); tradingeconomics.com (Oct 8: WTI $93.03, +5.38%); en.wikipedia.org 2026 Strait of Hormuz crisis / Economic impact of the 2026 Iran war (IEA: largest supply disruption in history); nbcnews.com (Oct 8: Trump pledge not to strike Iran before midterms fails to soothe oil markets); cnbc.com (Oct 6: tanker attacks, rebounding exports); theatlantic.com (Oct 7: Trump rejects 7-day Iranian plan)2026-10-06/08Tier 2Market Strip; Market Signals; Five Things; Data; Forecasts
8economictimes.indiatimes.com (Oct 7-8: eight firms expected for IndiaAI round two — Avataar.ai, Tech Mahindra, Fractal Analytics, Genloop, IntelliHealth, Shodha AI, Zenteiq, BharatGen; govt has not named beneficiaries)2026-10-07/08Tier 2Ecosystem; Data; Hiring; Forecasts
9Carried, unchanged: anthropic.com / venturebeat.com (Haiku 5.5); openai.com / openrouter.ai (Luna); mistral.ai / reuters.com (ML4 Oct 27); rbi.org.in / thehindu.com (repo 5.50%); reuters.com / llmgateway.io (GLM 5.3 Fast; Chinese catch-up); ekonomictimes.indiatimes.com / aninews.in / techgig.com (Naukri Sept); timesofindia.indiatimes.com / teamlease (IT structural shift); moneycontrol.com (orchestration battleground; GCC projections via Business Today); zinnov.com (GCC AI exposure); thehindubusinessline.com / deccanherald.com (TCS-Best Buy); microsoft.com (Digital Defense Report); anthropic.com (Frontier Academy); x.ai (Grok 4.7); blogs.nvidia.com (DGX Spark); aiweekly.co (AMD; Meta-Virtue; OpenAI Robinson exit); skillsyncer.com / trueup.io / layoffs.fyi / indiatoday.in (aggregates); ET BFSI / Whalesbook (RBI AI-stability); CXO Today / ET (BharatGPT); IBM-Yotta; Infosys; Wipro; Quess; Nomura; Anarock; NASSCOM Strategic Review; theinformation.com (89% concentration); pragativadi (WDR launch)2026-08/10Tier 1/2/3Ecosystem; Layoff Radar; Hiring; Real Estate; Data; Forecasts