Pan-India economic intelligenceSunday, November 1, 2026
AI2

Ai2India

Daily Edition

One daily issue tracking AI adoption, markets, hiring, layoffs, real estate, credit and gig-work signals across India.

PublishedNovember 1Daily issue
Nifty 50 (Oct 30 close)≈23,053↑116 pts (↑0.51%) — reclaimed 23,000; IT and pharma led (Nifty IT +2.5%, pharma +1.7%); Trent +5.2% on 25% Q2 profit growth; midcaps and smallcaps underperformed. Sunday; next trade Monday Nov 2.
Sensex≈74,460↑308 pts (↑0.42%) — second straight session of gains; IT-led recovery despite crude near $116 and weak Asian cues; consumer durables, energy, media fell 1%+
USD / INR≈95.22Rupee opened 4 paise stronger at 95.22 vs 95.26 Thursday close; RBI defence near 95 continues; crude at six-month highs keeps import-bill pressure intact
Brent Crude≈$116Crude at $116 as of Oct 30 — six-month highs; geopolitical risk premium intact after Gulf supply concerns; major import-cost headwind for India; capped gains in broader indices
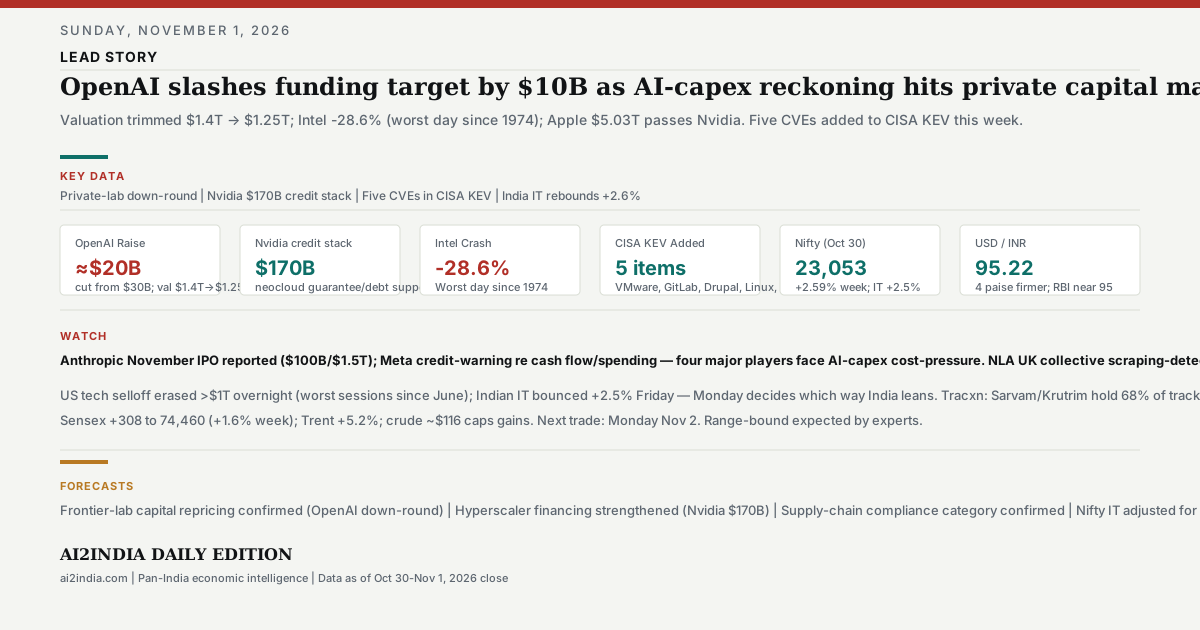
November 1, 2026 signal board: OpenAI slashes funding target by $10B to ~$20B, valuation $1.4T → $1.25T as AI-stock selloff deepens. Intel -28.6%, Apple $5.03T passes Nvidia.
Today’s economic signal board. Full analysis in the Daily Edition.
Full image description — 350 characters

November 1, 2026 signal board: OpenAI slashes funding target by $10B to ~$20B, valuation $1.4T → $1.25T as AI-stock selloff deepens. Intel -28.6%, Apple $5.03T passes Nvidia. Five CVEs added to CISA KEV this week including VMware ESX, GitLab exploitation. Tracxn: Sarvam/Krutrim hold 68% of tracked Indic-AI funding. Nifty reclaimed 23,000; IT +2.5%.

Lead Analysis

OpenAI slashes funding target by $10B as AI-capex reckoning hits private capital markets

Valuation trimmed from $1.4T to $1.25T; UAE investors and Coatue still leading a round that may land below even the revised $20B figure.

Sunday, November 1, 2026: OpenAI has cut its latest fundraising target by $10 billion to approximately $20 billion, lowering its post-money valuation target from $1.4 trillion to $1.25 trillion as a broad AI-stock selloff forces both public-equity and private-capital repricing. Some investors reduced their allocations and the first close may land below the revised figure.

The cut, reported by the Financial Times on October 31 and confirmed by CNBC, follows a week when public-market participants questioned whether big-tech spending on AI infrastructure -- data-centre builds and GPU procurement -- will deliver adequate returns. OpenAI set a Friday deadline for investor commitments; the UAE-backed sovereign fund remains the anchor alongside Coatue, with some investors opting to shrink their ticket sizes.

The public-market echo was starker still. On Thursday, Alphabet suffered its worst trading day ever after search revenue missed estimates -- partly because lower monetisation within its own AI Mode -- and Intel crashed 28.6%, its worst single day since 1974. By Friday, the semiconductor index had fallen 7.2%, the Nasdaq posted its worst session since June, and Apple crossed $5.03 trillion to reclaim top spot from Nvidia at $4.93T. Fortune reports Meta has also received a credit-warning alert over cash-flow and spending concerns.

For Indian enterprise, the signal is structural rather than tactical. The hyperscaler debt-financing lane opened by Amazon's $80B facility (Oct 31) is now reinforced: OpenAI's equity-round shortfall tells the same story, just on the private-lab side. Cloud-services demand for Indian SIs and GCCs stays high into 2027-28, but financing conditions -- particularly if the Fed raises in December -- become the swing factor in hyperscaler pricing and AI-investment pacing. Every Indian CFO and technology planner who models cloud-cost trajectories should fold rising financing costs into those projections.

On Indian markets, the juxtaposition could not be sharper. Friday saw Nifty reclaim 23,000 (+0.51%) with Nifty IT +2.5% leading the rebound -- the first IT-led advance since Infosys' guidance rout. But the US trillion-dollar tech selloff lands as the live risk for Monday's open. The AI-capex reckoning and Mumbai's technical bounce point in opposite directions: the former is the macro headwind, the latter is earnings-driven resilience (Trent +5.2%, IndiGo narrowing loss). For Indian AI-planners the durable takeaway remains: hyperscaler buildout is being financed through leverage, which keeps cloud-services demand strong for Indian suppliers while the market prices the debt load.

AI Developments Today

Sunday, November 1, 2026: Top AI stories with source, India relevance, and enterprise impact. Lead: OpenAI funds target cut $10B amid AI-stock selloff. Below: Intel -28.6%, Apple $5.03T passes Nvidia, Meta credit warning; Anthropic November IPO plans; CISA KEV adds five items this week; Washington Post Copilot ballot-brief errors.

StoryKey DetailsIndia RelevanceWhat This Means for Indian EnterpriseSource / Date
OpenAI slashes funding target by $10B as AI-stock selloff deepens
$30B → ~$20B raise; valuation $1.4T → $1.25T; some investors reducing allocations; round still open
Oct 31 (Bloomberg; CNBC; Financial Times via TechCrunch): OpenAI cut its fundraising target by $10 billion to approximately $20 billion, trimming valuation from $1.4 trillion to $1.25 trillion. UAE sovereign investors and Coatue continue to lead. First close may land below the revised $20B. Set a Friday deadline for investor commitments; some investors reduced ticket sizes. Follows a week of questioning big-tech AI capex ROI -- Google's worst day ever Thursday (search missed), Intel -28.6% Friday (worst day since 1974), chip index -7.2%, Nasdaq worst since June. Direct signal for every Indian AI planner: the private-lab capital markets are repricing AI-buildouts. OpenAI's funding shortfall mirrors what public markets did to hyperscalers last week -- demand-side confidence in AI ROI is contracting. For Indian cloud-SIs servicing AWS/Microsoft/Google/Azure workloads, the same financing-pressure story applies: if lab equity rounds underwrite to lower multiples, upstream demand for compute contracts may slow. (1) Fold OpenAI's down-round into vendor-risk assessments for any org running ChatGPT API-dependent products. (2) Track downstream effects on Anthropic, Mistral, DeepSeek and other private labs -- if they face parallel repricing, expect API-price compression or self-host push as the cheaper path. (3) Model cloud-cost projections with rising financing-cost overlays, not just operating-cash assumptions. Verified global — Bloomberg; CNBC; FT (Tier 1/2); Oct 31, 2026
Wall Street AI reckoning: Intel -28.6%, Apple passes Nvidia, Meta credit warning
Chip index -7.2%; Apple $5.03T overtakes Nvidia $4.93T; Nasdaq worst since June; Alphabet worst day ever
Oct 28-30 (Fortune; FourWeekMBA; CNBC): Alphabet search revenue missed estimates on Oct 28 -- Chief Business Officer Philipp Schindler said part of the shortfall came from lower monetisation within AI Mode. Intel crashed 28.6% on Oct 30 (worst day since 1974) on lackluster revenue guidance. Chip index fell 7.2%; Nasdaq posted worst session since June. Apple closed Oct 30 at $5.03T, retaking the #1 spot from Nvidia at $4.93T. Fortune reports Meta received a credit-rating warning concerning cash flow, spending and monetization. Global X AI ETF down 15% from summer highs. Analysts frame it as markets pricing AI build-outs as debt rather than growth. Public-market repricing of AI has direct consequences for Indian AI-planners: the thesis of 'AI capex = guaranteed growth' is no longer a consensus assumption in public-equity markets. Indian SIs whose growth narratives depend on hyperscaler capex tailwinds must now model downside scenarios where capital markets treat AI investment as leveraged risk rather than organic growth. Meta's credit-warning is particularly salient given the company's large Indian engineering workforce and growing AI features portfolio. (1) Update business cases that assume continued hyperscaler capex acceleration without counterweight scenarios. (2) Monitor Meta credit trajectory for downstream implications on AI-feature rollouts and Indian team composition. (3) Track the narrative shift -- 'AI as debt' vs 'AI as growth' -- as it feeds into Indian corporate planning cycles. Verified global — Bloomberg; CNBC; Fortune; FourWeekMBA (Tier 1/2); Oct 28-30, 2026
Anthropic plans November IPO reportedly targeting up to $100B
IPO planned; valuation target ~$1.5T; Nvidia guaranteeing billions in debt for 460MW Anthropic datacenter build
Oct 31 (britbrief.co.uk; The Information): Anthropic is reportedly planning a November IPO raising up to $100 billion at a $1.5 trillion valuation target -- positioning itself as the rival to OpenAI's pending round. Concurrently, Nvidia is in advanced talks to guarantee billions in debt for Nscale to build an additional 460MW phase of its Monarch campus in West Virginia, doubling Anthropic's capacity commitment under its six-year ~$45B deal. Nvidia has now layered roughly $170B in credit support and investments across neocloud customers. If Anthropic goes public at $1.5T, it becomes the largest AI-lab listing on record -- a benchmark that will reshape how Indian institutional investors and VC firms value domestic labs like Sarvam and Krutrim. The Nvidia credit-support stack ($170B already deployed) extends the hyperscaler-leverage pattern OpenAI's own down-round reflects. Monitoring the IPO filing timeline becomes essential for any Indian org benchmarking its AI-vendor choices against a newly-public, disclosed-cost base. (1) Track Anthropic's SEC filing for disclosure terms -- public reporting would provide Indian buyers with cost transparency unavailable in current private-lab relationships. (2) Monitor whether Nvidia's debt-guarantee pattern spreads to other neocloud providers as the industry-wide financing challenge intensifies. (3) Prepare Sarvam/Krutrim competitive positioning against a potential listed Anthropic offering. Reported global — britbrief; The Information (Tier 1/2); Oct 31, 2026
CISA KEV: five items added this week -- VMware ESX, Linux kernel LPE, Drupal Commerce Core, GitLab exploitation, Brotli decoder
Active exploitation confirmed across virtualisation, CI/CD, CMS, runtimes, and edge appliances
Oct 28-Nov 1 (CISA; BleepingComputer; CSA Singapore; Dreamgroup researchers): Two additions to KEV on Oct 28 -- CVE-2026-41709 (Broadcom VMware ESX insufficient logging) and CVE-2026-46300 (Linux kernel missing-initialisation LPE, chained with PHP2Shell on PAN-OS management servers per Dreamgroup campaign). Three non-KEV active-exploitation advisories: CVE-2026-118539 (Drupal Commerce Core access bypass, 42,000+ sites affected, advisory Oct 28/BleepingComputer Oct 31), CVE-2026-97229 (GitLab max-severity, CISA confirmed active exploitation Oct 31, federal patch deadline Sunday), CVE-2026-111497 (Brotli decoder used in Node.js, Microsoft and multiple products; Singapore CSA confirmed active exploitation Oct 30). Wide coverage across the full stack: VMWare ESX (every Indian datacentre using vSphere); Linux kernel (Ubuntu/RHEL endpoints across Indian dev shops and GCCs); Drupal (Indian e-commerce and government portals); GitLab (heavily used by Indian software shops and GCCs for CI/CD); Brotli/Node.js (Indian web-development ecosystem). Each carries distinct patch windows and exploit timelines relevant to Indian IT departments. (1) VMware ESX: verify ESXi patch status across all hosted environments. (2) Linux kernel LPE CVE-2026-46300: patch Ubuntu/RHEL hosts, especially those exposed to untrusted code execution pipelines. (3) GitLab CVE-2026-97229: patch CI/CD servers immediately -- CISA ordered federal remediation by Sunday Nov 1. (4) Brotli CVE-2026-111497: check Node.js installations running brotli compression for applicable patches. (5) Drupal Commerce: patch affected sites, especially any merchant-facing platforms. Verified exploited — CISA KEV alerts (Tier 1); BleepingComputer; CSA Singapore; Dreamgroup (Tier 1/2); Oct 28-Nov 1, 2026
Washington Post investigation: Microsoft Copilot cites AI-generated ballot brief in 75% of election test answers
ballotbrief.com cited in 75% of tests; ChatGPT cited it in 22%; 22% error rate in district-ID mapping across AI voter guides
Oct 30 (Washington Post): A Post investigation tested hundreds of AI-generated voter guides and found district identification errors in 22% of specified-district guides, driven by chatbots passing on Ballot Brief's wrong zip-code-to-district mappings. Microsoft Copilot cited the AI-produced ballotbrief.com in 75% of its election test answers; ChatGPT cited it in 22%. OpenAI's reliance dropped substantially after the Post made contact. Reputation risk for AI tools deployed in Indian civic-tech contexts: Indian e-governance platforms and legal-advisory tools using retrieval-augmented generation face analogous risks if ground truth data sources are not rigorously validated. Any Indian org deploying AI assistants for employee-facing queries (HR, compliance, policy help) should audit training-grounding data quality similarly. (1) Audit grounding/retrieval data sources in any Indian AI assistant -- ensure authoritative domains are the primary input. (2) Implement human-in-the-loop verification for time-sensitive informational content. (3) Document response quality benchmarks for internal RAG systems; the 75%/22% discrepancy between models demonstrates why vendor selection matters for information-critical applications. Verified global — Washington Post (Tier 1); Oct 30, 2026

India AI Ecosystem

Sunday, November 1, 2026: Tier-4 platforms, NASSCOM signals, MeitY policy, ecosystem developments. NEW THIS CYCLE: Tracxn Indic AI report -- Sarvam/Krutrim hold 68% of tracked funding, 87% of 2026 volume (Sarvam $389M cumulative / Krutrim $75M). Carried lanes updated: OpenAI round cut reframes competition dynamics for Indian labs; Anthropic IPO plans create benchmark effect.

Platform / SignalUpdateSource / Date
Tracxn Indic AI report: Sarvam/Krutrim hold 68% of tracked funding (NEW DATA)New Oct 29-30 report "Indic AI: Building AI for Bharat": Sarvam and Krutrim together account for $464M (68% of total tracked $687M across 34 companies). Of 2026-year funding, Sarvam accounted for $346M in two rounds (87% of sector totals). Sector raised $399M in 2026 / $687M cumulative. Sarvam's total funding stands at $389M; Krutrim at $75M.Analytics India Mag; Livemint; Ciol; CXO Today (Tier 1/2); Oct 29-30, 2026
OpenAI funding round reframes India-lab competition (UPDATE TO CARRIED)Oct 31: OpenAI's $10B target cut and valuation trim ($1.4T → $1.25T) sets a lower ceiling for the entire private-lab category. For Indian labs -- Sarvam ($389M), Krutrim ($75M), the MeitY incentive winners -- the benchmark has shifted. If the broader category trades down, fundability expectations for late-stage Indic labs adjust downward too.Based on carried Cognizant-Sarvam stake talks; updated for OpenAI down-round. Bloomberg; CNBC (Tier 1/2); Oct 31, 2026
Cognizant–Sarvam stake talks (carried)Oct 28-29: ET exclusive — Cognizant in talks to participate in Sarvam AI’s ≈$300M round at a $3.5–4B valuation. Reported, company-unconfirmed. First global IT-services equity stake in an Indian foundation-model lab if closed.Economic Times; Inc42 (Tier 1/2); Oct 28-29, 2026
MeitY DEPA-AI framework (carried)Oct 30: MeitY proposed Data Empowerment and Protection Architecture for AI Training — consent-based, developed with iSPIRT, letting startups train on hospital/bank/public-agency data without transfer ("sealed-room"). Draft cites $500B GDP value by 2030.Business Standard; Inc42; Livemint (Tier 1/2); Oct 30, 2026
NICSI AI modernisation empanelment (carried)NICSI looking to empanel up to 20 firms for government legacy-system AI modernisation (RFPs/RFQs/EOIs prepared).Moneycontrol AI Edge (Tier 2); Oct 30, 2026
Sarvam–HQ IDS defence MoU (carried)Oct 26: Sarvam signs MoU with HQ IDS for Army-Navy-Air Force AI framework covering operational, training and decision-support.Business Standard; Rediff (Tier 2); Oct 26-28, 2026
MeitY: AI-intermediary rules weighed (carried)Oct 28: Lawyers and Big Tech argue for AI-platform intermediary definition distinct from social-media rules. Safe-harbour delimitation is core contested question. Consultation paper due soon.Elets CIO (Tier 2); Oct 28, 2026
DPDP (Removal of Difficulties) Order, 2026 (carried)MeitY order clarifies guardian consent for children; changes audit language. Affects consent architecture in AI-driven data pipelines handling minor data.IMPRI (Tier 2); Oct 29, 2026
Krutrim workforce reduction (carried)Oct 25: Leadership exodus and workforce reduction; 60+ linguistics staff and AI leaders departed; funding dried up. Remains #2 in Tracxn Indic-AI tracked funding at ≈$75M.Economic Times (Tier 1); Oct 19, 22, 25, 2026
Karmayogi-OpenAI MoU (carried)Oct 21: OpenAI Academy integrated into iGOT Karmayogi platform for 1.7 crore government employees.ET; HBL; Rediff (Tier 1/2); Oct 21, 2026
NIELIT Quantum & AI University Campus, Amaravati (carried)HBL (Oct 26): Entirely grant-in-aid from MeitY for NIELIT quantum/AI campus; CRDA meeting chaired by AP CM.The Hindu BusinessLine (Tier 2); Oct 26, 2026
TCS / Infosys / HCLTech AI revenue figures (carried)Nikkei Asia (Oct 26): TCS AI revenue +19%+ YoY past 10% (~$3.1B annualized); Infosys AI revenue +29% QoQ ~10.5%; HCLTech advanced-AI $219M (+28.4% QoQ, +78% YoY CC).Nikkei Asia; HBL (Tier 2); Oct 26, 2026
IBM-Yotta sovereign platform (carried)Bengaluru: watsonx Orchestrate on Yotta Shakti Cloud with Studio fine-tuning.IBM-Yotta joint; Sep 29, 2026

AI Adoption Impact

Sunday, November 1, 2026: Enterprise AI adoption data, AI-driven hiring/layoff signals, productivity shifts. NEW this cycle: OpenAI down-round + MAG5 deleveraging reframe the AI-investment debate; NLA UK collective scraping detection reveals economics-of-AI-data; Murata ¥1T MLCC expansion quantifies AI-server supply chain scale. Carried lanes updated.

SignalData PointSource / DateTrajectory
OpenAI down-round / valuation trim (NEW)Fundraising cut from $30B to ~$20B; valuation $1.4T → $1.25T. UAE investors and Coatue leading; some investors reducing tickets; first close may land below $20B. Follows MAG5 return collapse (9.3% OCF to shareholders on $556.9B capex) and Amazon's $80B supplier-financing facility. Private-lab funding and public-equity markets converging on AI-as-debt thesis.Bloomberg; CNBC; FT (Tier 1/2); Oct 31, 2026Capital-markets repricing accelerating
MAG5 deleveraging continues (CARRIED WITH UPDATE)$556.9B combined capex exceeds $542.9B operating cash flow. Buybacks collapsed 83% to $13.6B. OpenAI down-round confirms same dynamic at private-lab level. Nvidia layers $170B in credit support across neocloud customers (including Anthropic 460MW). Public-equity and private-capital narratives converged on one theme: debt-financed AI buildout.AI Weekly analysis; The Information; Bloomberg (Tier 1/2); Oct 30-31, 2026Structural; leverage expanding across capital forms
Nvidia NEoCloud credit stack (NEW)Nvidia guaranteeing billions in debt for Nscale's 460MW Anthropic datacenter phase. Total credit support/investments across neocloud customers now ~$170B. Pattern: hardware vendor acting as de facto lender to AI-infrastructure builders -- a financing layer unique to the GPU-centric AI era.The Information via cryptobriefing (Tier 2); Oct 31, 2026New financing model emerging
NLA UK collective scraping-detection (NEW)NLA Media Access launched free Collective Intelligence Advisory Service pooling traffic data across 14,000 UK publication titles to identify invisible AI scrapers. Pilot identified operations in Eastern Europe and Asia-Pacific. CEO expects formal collective legal action within 18 months. Data-economics angle: publishers are weaponising shared telemetry to fight undervalued data extraction by AI labs.resultsense.com (Tier 2); Oct 30, 2026Data-rights enforcement accelerating
Murata ¥1T MLCC expansion for AI servers (NEW)Murata spending ¥1T ($6.3B) over five years to more than double MLCC output targeting 15,000–25,000 MLCCs per AI server. Already holds ~40% global MLCC market, >50% advanced AI-server share. Utilization near 95%. Supply-chain constraint quantified at component level.fourweekmba.com (Tier 2); Oct 31, 2026Supply-chain scaling required
US CS enrolment decline (CARRIED)Fall 2026 preliminary: CS enrolment -12.4% (4-yr), -12.3% (2-yr), -10.4% (grad); 2-year undergrad CS -18.4%, grad -27.1%.NSC Research Center (Tier 1); Oct 29, 2026Structural; education pipelines shifting
52% of Indian CEOs plan workforce cuts (CARRIED)PwC survey of 125 Indian CEOs: 52% plan AI-driven workforce reductions; 87% focus on retaining/retraining high-potential employees.PwC via BusinessToday (Tier 2); Oct 28, 2026Structural; planning stage
Innodata ~550 India layoffs (CARRIED)~550 India roles cut Oct 26 (laptop access shut before termination email; letter cited ramp-down). Additional reductions in Philippines.NDTV; CIOL; Inc42 (Tier 2); Oct 26-29, 2026AI-services rationalisation
Xpheno six majors net -24K headcount (CARRIED)TCS, Infosys, HCLTech, Wipro, TechM, LTIMindtree combined 822,144 → 797,722 (Oct 2025-26); ~92K exits vs ~68K intake.Xpheno via ET (Tier 2); Oct 23, 2026Confirmed downward
GCC hiring caution (CARRIED)Avg headcount per India GCC stalls near 1,115; ~65% of new GCC roles require AI skills (ANSR).ANSR; Outsource Accelerator (Tier 2); Oct 20-24, 2026Structural shift
LLM price collapse (CARRIED)Mistral Large 4 API cited at $0.70/$2.10 per M tokens with open weights. Globally: Luna $0.20/$1.20; Terra $1/$5; Sonnet 5 $2/$10; Gemini 4 Carbon $2/$10 intro.Vendor pricing; AI Weekly (Tier 1/2); Oct 29-30, 2026Floor expanding; self-host option new

Five Things That Changed

Sunday, November 1, 2026: 3 AI items, 1 India-policy/data item, 1 markets item — each with verified data and source.

SignalData PointReader ImpactStatus
1. OpenAI slashing funding target by $10B (Bloomberg; CNBC; FT, Oct 31): Fundraising cut from $30B to ~$20B; valuation trimmed from $1.4T to $1.25T. Round still open but first close may land below revised figure. Follows a week of public-market AI-repricing: Alphabet worst day ever (Thursday), Intel -28.6% (Friday, worst since 1974), chip index -7.2%, Apple $5.03T passes Nvidia. This is the clearest signal yet that AI-investment finance is entering a repricing phase. What began as public-equity scepticism about hyperscaler AI capex (Amazon $80B facility, MAG5 9.3% OCF return, Intel crash) has reached private-capital markets. The implication for Indian AI planners: every future AI-lab funding round -- including Sarvam, Krutrim, Inflection, and others -- will face tighter valuation discipline and potentially smaller cheque sizes from the same investor pool. Adjust vendor-selection and budgeting models: if AI-lab equity rounds come in smaller, expect accelerated self-host/open-weight shifts as labs prioritise efficiency over feature breadth. Include financing-health metrics in your AI-vendor risk scorecard. Verified global — Bloomberg; CNBC; FT (Tier 1/2); Oct 31, 2026
2. CISA KEV expands: five items added this week across the full stack (CISA; BleepingComputer; CSA Singapore; Dreamgroup, Oct 28-Nov 1): VMware ESX CVE-2026-41709 (insufficient logging, KEV Oct 28) and Linux kernel LPE CVE-2026-46300 (KEV Oct 28, chained with PHP2Shell on PAN-OS per Chinese-nexus Dreamgroup campaign). Plus three actively exploited non-KEV items: Drupal Commerce Core CVE-2026-118539 (42,000+ sites affected), GitLab max-severity CVE-2026-97229 (CISA confirmed active exploitation Oct 31, federal patch deadline Sunday), Brotli decoder CVE-2026-111497 (Singapore CSA confirmed active exploitation, affects Node.js and Microsoft products). Wide coverage across every critical infrastructure layer: virtualisation (VMware), OS kernel (Linux), CMS/e-commerce (Drupal), CI/CD tooling (GitLab), and web-runtime compression (Brotli/Node.js). Indian datacentres running vSphere, Indian dev shops using GitLab, Indian e-commerce running Drupal, and Indian web stacks on Node.js are all directly exposed. The Dreamgroup chained-campaign detail (PHP2Shell + kernel LPE on PAN-OS targeting US-government-affiliated targets) confirms ongoing active exploitation beyond the patch date. Immediate patch windows: GitLab CI/CD servers (CISA federal deadline Sunday), VMware ESXi across all hosted environments, Ubuntu/RHEL kernel patches, Node.js brotli modules, and Drupal Commerce Core modules. Treat the Dreamgroup chained-campaign as evidence of sophisticated multi-flaw exploitation: single-flaw patching is no longer sufficient threat modelling. Verified exploited — CISA KEV alerts (Tier 1); BleepingComputer; CSA SG; Dreamgroup (Tier 1/2); Oct 28-Nov 1, 2026
3. Meta receives credit-warning alert over cash flow and spending (Fortune, Oct 31): Meta's enormous AI-spending trajectory -- estimated ~$60B+ annual capex -- has triggered a credit-rating agency review noting cash-flow sufficiency and monetization concerns. Concurrently, Nvidia layers credit support (now $170B across neocloud customers) suggesting the hardware vendor is becoming a de facto financing backstop for the AI buildout. Global X AI ETF down 15% from summer highs. A credit-warning for the world's most visible AI-spender carries systemic implications: if one entity needs credit-signal adjustment for AI capex, the sector's overall borrowing cost rises, and every AI-plan dependent on hyperscaler availability becomes harder to finance. For India, Meta employs ~3,600+ engineers across Bengaluru and Hyderabad -- credit stress could trigger restructuring in the company's Indian presence, adding to the PwC survey's 52% of Indian CEOs planning workforce reductions. Monitor Meta credit trajectory for downstream effects on AI-feature availability and Indian team structures. Model cloud-pricing sensitivity to rising financing costs in India. Expect Nvidia to continue its neocloud financing role as the bridge between hardware sales and customer build-out. Verified global — Fortune (Tier 1/2); Oct 31, 2026
4. Tracxn Indic AI: Sarvam/Krutrim hold 68% of tracked funding (Analytics India Mag; Livemint; Ciol, Oct 29-30): Sarvam ($389M cumulative) and Krutrim ($75M cumulative) account for $464M, or 68% of $687M across 34 tracked Indic-AI companies. Sarvam alone captured 87% of 2026-sector funding ($346M in two rounds). With the OpenAI down-round setting a lower ceiling for private-lab valuations, the Indic-AI benchmark has shifted. Coincides with Cognizant-Sarvam stake talks at $3.5-4B reported valuation (company-unconfirmed). The concentration ratio (68%) underscores that Indic AI remains a two-player race with long tails. Sarvam's dominance (87% of 2026 volumes) and reported international interest (Cognizant stake) position it uniquely if the broader category trades down post-OpenAI round. Conversely, Krutrim's leadership exodus and funding dry-up contrast sharply with Sarvam's momentum -- the gap widens. Include the OpenAI down-round in Sarvam's competitive-positioning calculus: if foreign-lab valuations compress, domestic labs face both opportunity (cheaper foreign competition) and pressure (lower fundability expectations). Monitor Cognizant-Sarvam deal for precedent-setting cross-border IT-services equity stakes in foundational-model labs. Verified India — Analytics India Mag; Livemint; Ciol; CXO Today (Tier 1/2); Oct 29-30, 2026
5. Indian markets end week up: Nifty +2.59%, Sensex +1.6% (Livemint; IBTimes; BusinessToday, Nov 1): Nifty reclaimed 23,000 Friday closing at 23,053.10 (+0.51%), IT +2.5%, pharma +1.7%. Week gain 2.59% and 1.6% respectively, led by pharmaceutical and IT stocks. Experts expect range-bound Nov 2-6 trading with oil-price volatility as key variable. Diwali week approaching. Crude ~$116 caps upside. Friday's technical rebound (+2.59% week) against overnight US tech selloff (-$1T erased) creates divergent momentum: domestic earnings strength (Trent +5.2%, IndiGo narrowing loss) vs global AI-capex repricing. Range-bound expectation for next week is consistent with the macro uncertainty: Indian equities caught between supportive domestic liquidity and adverse global capital-markets narrative on AI debt. Next-week outlook (Nov 2-6) hinges on Monday US market open. If AI-stock selloff carries through Nasdaq, Indian IT could reverse Friday's gains. If US stabilises, earnings momentum (Diwali week ahead) supports continuation. Monitor crude for import-bill sensitivity. Verified India — Livemint; IBTimes; BusinessToday (Tier 2); Nov 1, 2026

Data Variables Ledger

Sunday, November 1, 2026: Key numbers for AI and economy trackers. Updated with verified data from Oct 28-Nov 1. Markets reflect October 30 close (Sunday; next trade Monday Nov 2).

VariableCurrent ValuePrior ValueChangeSource / Date
OpenAI funding target (NEW)Reduced to ~$20B from $30B; post-money valuation trimmed from $1.4T to $1.25T. Round still open; first close may land below revised figure. UAE sovereign + Coatue leading; some investors cutting allocations.$30B target / $1.4T valuation (reported Aug-Oct)$10B target cut; 10.7% valuation drop; private-lab equivalent of public-equity deleveraging.Bloomberg; CNBC; FT (Tier 1/2); Oct 31, 2026
Intel market cap / stock (NEW)Crashed 28.6% on Oct 30 (worst single day since 1974) on lackluster AI-chip revenue guidance. Semiconductors index fell 7.2%.Pre-crash levelsLargest single-day percentage decline in Intel's history.CNBC; FourWeekMBA (Tier 1/2); Oct 30, 2026
Apple passes Nvidia (NEW)Apple $5.03T market cap retakes #1 from Nvidia $4.93T as semiconductors fall.Nvidia #1; Apple #2 (for weeks)First #1 swap since Apple surpassed Nvidia earlier this year.FourWeekMBA (Tier 2); Oct 30, 2026
CISA KEV additions (NEW)5 items this week: CVE-2026-41709 (VMware ESX, exploited, KEV Oct 28); CVE-2026-46300 (Linux kernel LPE, exploited, KEV Oct 28); CVE-2026-118539 (Drupal Commerce, exploited, 42k+ sites); CVE-2026-97229 (GitLab, exploited per CISA Oct 31); CVE-2026-111497 (Brotli/Node.js, exploited per Singapore CSA Oct 30).Last update Oct 30 (CISA KEV had 28 entries added in October total)Five new active-exploitation events across full stack this week.CISA; BleepingComputer; CSA Singapore; Dreamgroup (Tier 1/2); Oct 28-Nov 1, 2026
Phrasing change (CARRIED, STATUS UPDATED)PHP2Shell (CVE-2026-109618/109619): Dreamgroup researchers confirm Chinese-nexus campaign chaining PHP2Shell + kernel LPE to root 24 firewalls plus one internal mgmt box (US, Japan, Taiwan, SK) including two US-gov targets. Forensic traces attribute development to DeepSeek, Kimi, and Claude Code sessions; reverse SSH tunnel into US-gov infra may still be live.Previously: exploited, PoCs circulating, cloudflare attacks observed.Chained-exploitation campaign adds sophistication signal; confirms ongoing active use beyond initial PoC window.Dreamgroup blog (Tier 2); AI Weekly recirculation; Oct 30, 2026
Sensex (UPDATED)≈74,460 (Oct 30; ↑308.49 pts, ↑0.42%); +1.6% for the week74,151.04 (Oct 29; ↑905 pts)Second straight gain; week +1.6%. Friday rebound vs US tech selloff divergence.Zeebiz; Moneycontrol (Tier 2); Oct 30, 2026
Nifty 50 (UPDATED)≈23,053 (Oct 30; ↑116.35 pts, ↑0.51%); +2.59% for the week22,936.75 (Oct 29)Reclaimed 23,000; week +2.59%; Nifty IT +2.5%Zeebiz; Business Standard (Tier 2); Oct 30, 2026
USD / INR (UPDATED)≈95.22 (Oct 30 open; 4 paise stronger)≈95.28 (Oct 29)Rupee firm; RBI defence near 95 intactNDTV; HDFC Sky (Tier 2); Oct 30, 2026
Brent Crude (UPDATED)≈$116 (Oct 30)≈$115 (Oct 29)Six-month highs; geopolitical risk premiumHDFC Sky; NDTV (Tier 2); Oct 30, 2026
Tracxn Indic AI 2026 (NEW)Sarvam + Krutrim = $464M / 68% of $687M tracked. Sarvam alone = 87% of 2026 volumes ($346M in two rounds). Cumulative: Sarvam $389M, Krutrim $75M.N/A -- new dataset this cycleHighly concentrated; two-firm dominance confirmed.Analytics India Mag; Livemint; Ciol; CXO Today (Tier 1/2); Oct 29-30, 2026
Repo rate (carried)5.50% (RBI); Fed held 3.75-4.00% (Oct 28, 10-2; December hike expected).UnchangedFed overlay unchanged.RBI; The Street (Tier 1/2); Oct 7-29, 2026
Global X AI ETF (NEW)Down 15% from summer highs as markets price AI build-outs as debt rather than growth.Summer 2026 peak15% drawdown reflects sector-wide repricing.FourWeekMBA analysis (Tier 2); Oct 30, 2026

Verified Layoff Radar

Sunday, November 1, 2026: India-confirmed only. No new India-specific layoff events this cycle. Carried rows stand. Meta credit-warning noted as caution signal, not a layoff count.

CompanyIndia ImpactDriverSource / DateStatus
Innodata ~550 laid off (carried)US data/AI services firm cut ~550 India roles on Oct 26 (laptop access shut before termination email; letter cited ramp-down); additional reductions in Philippines. India-specific official count undisclosed.AI-services industry rationalisation (data preprocessing/annotation workflows) + ramp-down cited in letterNDTV; CIOL; Inc42 (Tier 2); Oct 26-29, 2026Reported India — Delhi engineer confirmed; company-undisclosed India split
52% of Indian CEOs plan workforce cuts (carried signal)PwC survey of 125 Indian CEOs (Aug 11-Sept 21, 2026): 52% plan AI-driven workforce reductions; 87% prioritise retaining/retraining high-potential employees.AI-driven restructuring planning across sectorsPwC via BusinessToday (Tier 2); Oct 28, 2026Signal — planned, not executed
Microsoft 60K voluntary buyouts (carried)India explicitly eligible; no India headcount disclosed; voluntary; participation unknown.AI-era workforce restructuring + capital efficiencyCNBC; Bloomberg; NYT (Tier 1); Oct 26, 2026Verified global — India eligible; no India count
India GCCs -- aggregate estimate (carried)ThePrint: ~4,000-5,000 GCC layoffs estimated in India 2026 as AI reshapes team structures; avg headcount per GCC stalls near 1,115. Industry estimate.AI adoption + right-sizing GCC footprintsThePrint (Tier 2); ANSR; Outsource Accelerator; Oct 20-24, 2026Reported India — estimate, no company split
Krutrim workforce reduction (carried)Over 60 linguistics staff + AI/semiconductor leaders departed; funding dried up; plans shrinking.Funding contraction + product demand weaknessEconomic Times (Tier 1); Oct 19, 22, 25, 2026Reported India — confirmed by ET
Six IT majors net -24K headcount (carried)Xpheno: combined 822,144 → 797,722; ~92K exits vs ~68K intake (Oct 2025-26).AI adoption + bench managementXpheno via ET (Tier 2); Oct 23, 2026Verified India — net attrition
Top-5 IT Q2 results (carried)Infosys FY27 guidance cut; TechM +32.7%; Wipro -1.4%; TCS +15% PAT; HCLTech +21.2%. AI share expanding, margins compressing; Nifty IT +2.5% Friday.AI-augmented delivery; demand rebalancingLivemint; Nikkei Asia; FT (Tier 1/2); Oct 28, 2026Verified India — mixed; Infosys guidance cut
Oracle India (carried)≈3,000 employees potentially affected; India split company-undisclosed.AI/cloud-infrastructure redirectTimes Now; Fortune India; Sep 2026Reported India — company-undisclosed
US PERM suspension (carried)TCS, Infosys, Wipro, HCLTech, Cognizant, Capgemini, Microsoft, Adobe barred Oct 8. Pending frozen.US labour-policy actionTOI; Indian Express; Hindu (Tier 1/2); Oct 8-10, 2026Verified India relevance — no headcount impact
Indian IT structural shift (carried)FY26 net reduction ~7K (top-5) vs +12.7K FY25; campus hiring at two-decade low.AI-augmented delivery + precision hiringTeamLease; Naukri; Xpheno (Tier 2); Oct 1-23, 2026Verified India — structural shift

Hiring Demand Watch

Sunday, November 1, 2026: AI/cloud/cybersecurity roles vs general IT focus. NEW this cycle: OpenAI SDK agent-context-compaction creates new DevOps skill demand; Oracle TPU/Anthropic datacenter builds create localised hiring lanes; security-skill demand elevated by KEV wave. Carried lanes stand.

SegmentSignalData PointSource / Date
OpenAI SDK agent context controls (NEW)SDK compaction creates skill demandPython SDK 3.42.0 shipped Oct 31 with configurable context compaction, agent session review, tool settings, time awareness, external key management. Teams needing expert control over agent memory lifecycles -- summarisation strategy, blocking/background modes, scheduled runs -- become scarce profiles.unite.ai (Tier 2); Oct 31, 2026
Anthropic IPO runway (NEW signal)$100B IPO preparation hiresIf Anthropic proceeds on reported November IPO timeline, pre-IPO preparation teams hire aggressively across financial, legal, IR, and scaling ops. Experienced hires from US/Europe may be offset by expanded India engineering hiring for post-listing cost structure optimisation.britbrief; The Information (Tier 1/2); Oct 31, 2026
Security-skill surge from KEV wave (NEW signal)Five CVEs this week = urgent hiring for patch-response capabilityTeams fluent in CI/CD security (GitLab), kernel hardening (Linux CVE-2026-46300), browser-compression auditing (Brotli/Node.js), and CMS protection (Drupal Commerce Core) command premium rates during vulnerability waves. CISO hiring heat stays elevated across Indian GCCs.CISA; BleepingComputer; CSA Singapore (Tier 1/2); Oct 28-Nov 1, 2026
Self-host / open-weight inference roles (carried)Mistral Large 4 release drives demand1T-total/49B-active MoE with FP8/NVFP4 serving paths; teams able to stand up, quantise and fine-tune open weights inside regulated estates remain the scarce hire.Hugging Face; DEV Community (Tier 1/2); Oct 29-30, 2026
Sarvam scale-up hiring (carried signal)Round-dependent headcount expansionProposed ≈$300M round at $3.5–4B (reported) would fund compute and team expansion across Indic-language model R&D, defence-AI and enterprise deployment.Economic Times; Inc42 (Tier 1/2); Oct 28-29, 2026
52% CEOs plan cuts; 87% retain top talent (carried)Dual signal: planned reductions, high-potential retentionPwC 125-CEO survey: 52% plan AI-driven workforce cuts; 87% retain/retrain high-potential staff.PwC via BusinessToday (Tier 2); Oct 28, 2026
GCC AI-skills demand quantified (carried)65% of new roles need AI skillsANSR: nearly 65% of new GCC roles in India 2026 require AI skills; avg headcount per centre near 1,115.ANSR (Tier 2); Oct 23-24, 2026
NASSCOM/Taggd AI deficit (carried)AI demand +300% vs 2024; 53% skill deficitDecoding Jobs 2026: AI talent demand +300%+ vs 2024; 53% AI skill deficit.NASSCOM/Taggd (Tier 2); Oct 24, 2026
AI/ML hiring vs white-collar market (carried)Naukri JobSpeak SeptemberWhite-collar +2% YoY; AI/ML +20% YoY (record); IT-services recruitment subdued.ET; ANI (Tier 2); Oct 2-3, 2026
DPDP compliance roles (carried)NASSCOM x MeitY workshops16-city DPDP implementation workshops through Jan 2027; DPDP leads, privacy engineers.NASSCOM; IMPRI (Tier 2); Oct 7-29, 2026

Real Estate Pulse

Sunday, November 1, 2026: GCC and AI-company office moves. Hermantown approved 1.7M-sq-ft Google data center (500MW) in US -- notable but outside India scope. Carried India rows stand.

Company / ProjectLocationDetailStatus
TCS Hyderabad data-centre project (carried)Hyderabad₹70,000 crore DC project announced Q2 -- largest single AI-infrastructure commitment.Verified India — TCS; Oct 8-9, 2026
Microsoft Hyderabad region (carried)HyderabadLaunched Sept 21; three availability zones; zero-water cooling; AI-workload focus.Verified India — Sept 21, 2026
GCC space demand (carried)Top 7 citiesGCCs leased 19.2M sq ft in H1 2026 (45% of gross); Anarock sees 8-12M sq ft expansion; Zinnov-NASSCOM: 2,117 GCCs / 2.36M professionals.Verified India — ANAROCK; Zinnov; Oct 2026
Shillong Tech Park-II (carried)ShillongStaffFlex, Shamrock AI, Alorica, AI Centre of Excellence under IndiaAI Mission.Verified India — Highland Post; Sept 24, 2026
IndiaAI CoE Bhubaneswar (carried)BhubaneswarBlue Cloud Softech Industry Partner; ₹4 cr investment.Verified India — Business Standard; Sept 15, 2026
HCLTech Odisha AI DC + Tech Hub (carried)Bhubaneswar$1.48B AI DC with Sarvam; 5,000-seat hub; 6,000 jobs.Verified India — Reuters; Jul 2026
Infosys-Truist GCC (carried)IndiaInfosys and Truist announce strategic collaboration to build a GCC in India.Verified India — Infosys (Tier 1); Oct 19, 2026
Telangana Green Skills & Applied AI CoE (carried)HyderabadCentre opened with Microsoft, 1M1B, MeitY Startup Hub.Verified India — Careerindia (Tier 2); Oct 24, 2026

Market Signals

Sunday, November 1, 2026: Brief context only — Sensex, Nifty, INR, crude as 4 ticker cards. Next trade: Monday Nov 2.

Nifty 50↑2.59% week≈23,053 (Oct 30 close; +116 pts on day); reclaimed 23,000; Nifty IT +2.5%; pharma +1.7%; next trade Monday Nov 2
Sensex↑1.6% week≈74,460 (Oct 30 close; +308 pts on day); second straight gain; Trent +5.2% on 25% Q2 profit jump; next trade Monday
USD / INR≈95.22Rupee opened 4 paise stronger (95.22 vs 95.26); RBI defence near 95 intact; crude ~$116 keeps import-bill pressure on
Brent Crude≈$116Six-month highs; geopolitical risk premium intact after Gulf supply concerns; a direct headwind for India’s import bill and inflation

Markets closed Sunday. Friday's Indian rebound (+2.59% Nifty week) contrasts sharply with the US trillion-dollar tech selloff: Intel -28.6% (worst day since 1974), semiconductors -7.2%, Nasdaq worst since June, Apple $5.03T passes Nvidia, Alphabet worst day ever. The divergence frames Monday's open: does India's earnings-driven stability (Trent, IndiGo) win over or get swallowed by the global AI-capex repricing? Next week (Nov 2-6) expected range-bound by experts, with crude as the wildcard. Diwali week ahead.

Forecast Tracker Updates

Sunday, November 1, 2026: New forecast added — frontier-lab capital markets repricing (confirmed by OpenAI down-round, Anthropic IPO plans, Nvidia credit stacking); Hyperscaler financing forecast strengthened; Nifty IT call adjusted for US-Europe divergence. All Oct 29-31 forecasts carried with adjustments.

All carried forecasts from Oct 31 edition retained with status adjustments shown below.

ForecastStatusConfidenceLatest Evidence (Oct 31-Nov 1)
Frontier-lab equity capital repricing (NEW)Confirmed immediately — OpenAI down-round + Anthropic IPO + Nvidia credit stackHighOct 31: OpenAI cut target $30B→~$20B, valuation $1.4T→$1.25T. Simultaneously, Anthropic plans $100B November IPO at $1.5T; Nvidia guarantees billions for Anthropic's 460MW build ($170B total credit stack). Both sides of the private-lab spectrum: one repricing, one preparing to list. This convergence on capital-market constraints is the dominant thesis shaping all AI investment this quarter.
AI developer-tool supply chain becomes a compliance category (CONFIRMED)Confirmed — trojanized Claude Code + EMBRACE browser breaksHighNo change since Oct 31. Extension marketplace provenance, agent-permission governance, and hashed installs are now procurement criteria for Indian enterprises within two quarters.
Hyperscaler AI buildout shifts to capital-markets funding (STRENGTHENED)Strengthened — OpenAI down-round confirms private-lab parityHighOct 31: OpenAI's $10B cut parallels Amazon's $80B facility announcement. The same thesis plays in both public-equity and private-capital markets: AI buildouts are being priced as debt rather than organic growth. Expect at least one more hyperscaler to announce asset-backed financing within two quarters; private labs follow suit as the same investor pool tightens allocation discipline.
India unlocks proprietary data for model training (ACTIVE)Active — MeitY DEPA-AI draft publishedMediumUnchanged since Oct 31. Watch: consultation draft details, data-holder opt-ins, DPDP interaction within next two quarters.
IT services majors take equity stakes in Indian foundation-model labs (ACTIVE)Active — Cognizant–Sarvam talks continueMed-HighOpenAI down-round may affect Sarvam's negotiating position: if private-lab valuations compress, TCS/Infosys/Wipro following with stake purchases becomes more affordable but less accretive to portfolio. Watch.
Open-weight frontier reasserts outside US-China axis (CONFIRMED)ConfirmedHighUnchanged since Oct 31. Mistral Large 4 API pricing at $0.70/$2.10. Kimi K3.1 Pro weights still scheduled Nov 4.
Compute financing concentration creates threshold effect (STRENGTHENED)Strengthened — Nvidia $170B credit stackHighOct 31: Nvidia now the de facto lending institution for AI-neocloud. $170B in credit support/investments across customers. Fed December-hike path raises cost of GPU-finance; CoreWeave CDS previously noted elevated (>10%).
Big-Tech AI-era workforce retooling accelerates (ACTIVE)Active — Microsoft 60K buyouts + OpenAI down-round pressuresMed-HighMeta credit-warning adds a fourth major player (after Meta 15%, MSFT 60K, PwC 52%) facing AI-capex cost-pressure. Watch execution announcements through November.
Custom inference and caching reshape API cost curve (ACTIVE)ActiveHighUnchanged.
Enterprise agent platforms consolidate around 2-3 universal agents (WEAKENED)Weakened — supply-chain event + diverse model arrivalsMed-LowUnchanged since Oct 31 assessment.
Multi-model access becomes cloud-agnostic procurement default (CONFIRMED)ConfirmedHighUnchanged.
US enters an AI enforcement era (ACCELERATED)Accelerated — CMA Meta probe + MEK + CISA KEV expansionsHighOct 30: UK CMA opened formal investigation into Meta's publisher-content terms; Meta paused rollout. Five new CVEs in CISA KEV this week expand the enforcement surface. In India, the AI-intermediary debate parallels both.
INR depreciates to 97+ on crude > $85 (WEAKENED — contradicted again)ContradictedLowOct 30: Rupee 95.22 despite crude ~$116 and Fed hike pending. RBI intervention continues to cap the slide.
Nifty IT outperforms Nifty 50 in FY27 (ADJUSTED — US-divergence scenario)Under pressure but qualifiedMedOct 30-Nov 1: Nifty IT +2.5% Friday (+2.59% week) vs Nasdaq worst since June. Domestic earnings strength (IT + pharma) provides countercurrent to global selloff. If Monday US open sees further AI-stock selling, divergence widens; if US stabilises, IT continuation likely. Forecast splits along the Monday-open outcome.
Repo cycle: 5.50%, calibrated tightening (CARRIED)Stable domestically; Fed December hike narrows RBI flexibilityHighUnchanged.
AI hiring share of IT vacancies >15% by H2 FY27 (ON TRACK)On track — security-skill surge from KEV waveHighOct 31: Five-CVE wave creates immediate demand for patch-response, CI/CD security, kernel hardening, and CMS-protection skills. NSAAN 65% AI-skills requirement and Naukri AI/ML +20% YoY keep the track intact.

Source Notes

Sunday, November 1, 2026: All cited sources, sorted chronologically by date, with source tier classification. Only sources used in this edition. No fabricated citations.

#SourceDate RangeTierSections Used In
1Bloomberg "OpenAI Funding Target Cut by $10 Billion"; CNBC "OpenAI pares fundraising goal, now seeking up to $20 billion"; Financial Times (via Bloomberg/CNBC/OpenAI): OpenAI cut $30B→~$20B target; valuation $1.4T→$1.25T; UAE + Coatue leading; some investors cutting allocations; Friday deadline set; round still open, first close may land below $20B.Oct 31, 2026Tier 1/2Lead; AI Dev #1; Five Things #1; Data
2Fortune "AI boom hits a wall on Wall Street as OpenAI cuts fundraising target while Meta gets a credit warning over its cash flow, spending and monetization" (Oct 31); FourWeekMBA "Apple passes Nvidia at $5.03T as AI capex fears hit chips" (chip index -7.2%, Nasdaq worst since June); Intel -28.6% (worst day since 1974); Metacredit-warning narrative. Global X AI ETF -15% from summer highs.Oct 30-31, 2026Tier 1/2AI Dev #2; Lead; Five Things #3; Data
3britbrief.co.uk: "Anthropic plans November IPO reportedly targeting up to $100B at $1.5T valuation". cryptobriefing/The Information: Nvidia guaranteeing billions in debt for Nscale 460MW Anthropic datacenter phase; $170B credit stack across neocloud.Oct 31, 2026Tier 1/2AI Dev #3; Adoption; Five Things #3; Forecast
4CISA KEV: two additions Oct 28 -- CVE-2026-41709 (Broadcom VMware ESX insufficient logging) and CVE-2026-46300 (Linux kernel missing-initialisation LPE); CVE-2026-97229 GitLab max-severity, CISA confirmed active exploitation Oct 31, federal patch deadline Sunday. Dreamgroup researchers: Chinese-nexus campaign chains PHP2Shell (CVE-2026-109618/109619) + kernel LPE to root 24 firewalls + one mgmt box (US, Japan, Taiwan, SK) including two US-gov targets, forensic traces attribute to DeepSeek/Kimi/Claude Code sessions. CSA Singapore al-2026-154: CVE-2026-111497 Brotli decoder, active exploitation confirmed Oct 30 (affects Node.js, Microsoft). BleepingComputer via TechBytes: CVE-2026-118539 Drupal Commerce Core, active exploitation, 42,000+ sites, advisory Oct 28.Oct 28-Nov 1, 2026Tier 1/2AI Dev #4; Five Things #2; Data; Forecast
5Washington Post (Oct 30): Copilot cited AI-built ballotbrief.com in 75% of election test answers; ChatGPT 22%; 22% district-ID error rate across AI voter guides.Oct 30, 2026Tier 1AI Dev #5
6Analytics India Mag: "Indic AI Funding Trends: Sarvam Dominates 2026" ($687M total, 34 companies, Sarvam/Krutrim 68% / $464M); Livemint: "Sarvam-led funding surge takes India's Indic AI investments to $687 mn" (Sarvam 87% of 2026 volumes, $346M in two rounds); Ciol: "Sarvam AI Drives 87% of India's Indic AI Funding in 2026"; CXO Today/Liva Mint corroborating. Sarvam $389M cumulative, Krutrim $75M.Oct 29-30, 2026Tier 1/2Ecosystem; Five Things #4; Data
7Livemint: "Stock market prediction Nov 2-6 week: Nifty, Sensex rebound from losses" (Nifty +2.59%, Sensex +1.6% week, range-bound outlook); IBTimes India: "Sensex, Nifty extend gains for second day as IT, pharma stocks lead rally"; BusinessToday: "Markets Next Week: Will earnings-driven recovery continue amid elevated crude prices?"Nov 1, 2026Tier 2Five Things #5; Market Signals
8unite.ai: "OpenAI's four-layer monitors flagged DNS escape in 15 minutes" (activation probes, model-based reviewer, investigative agents, network telemetry). AI Weekly/October Monthly Recap: GPT-6.1 cancelled, Liquid AI LFM3, Gemini 4 Carbon, Pika H3 Flex, Moonshot closes Kimi K2 (Oct 31), Shared ChatGPT link flaw patched (P1, bounty $5K), OpenAI Model Spec update + Fair-use copyright brief.Oct 26-31, 2026Tier 2Adoption; Hiring; Forecast
9Carrried from prior editions unchanged: Economic Times (Cognizant-Sarvam talks; Krutrim exodus); Inc42; Business Upturn; PwC 52% CEO survey; Microsoft 60K buyouts; Anthropic S-1 background; Blackstone IPO warning; Xpheno -24K; GCC 1,115 avg; ANSR 65% AI skills; NASSCOM +300%; Naukri AI/ML +20%; Oracle India; US PERM; Repo 5.50%; Sarvam-HQ IDS; FT >10% AI revenue; Infosys Q2; TCS/Infosys/HCL revenue; NIELIT Amaravati; Karmayogi-OpenAI; IBM-Yotta; DPDP workshops; Layoffs.fyi; CoreWeave CDS; Fed 3.75-4.00% Dec-hike path; Brent $115-116; VAPOR PANDA/ARTEX; Cursor trojan; Amazon $80B; robots.txt token.Oct 2026Tier 1/2/3All sections; extensive carried baseline