Pan-India economic intelligenceFriday, October 30, 2026
AI2

Ai2India

Daily Edition

One daily issue tracking AI adoption, markets, hiring, layoffs, real estate, credit and gig-work signals across India.

PublishedOctober 30Daily issue
Nifty 50 (Oct 29 close)≈22,936↑≈237 pts (↑≈1.0%) — reclaimed 22,900; FMCG and financials led; early gains in IT heavyweights (TCS +1.54%, Infosys +0.83%); Adani Ports, Kotak Bank top gainers
Sensex≈74,151↑905 pts (↑≈1.2%) — sharp rebound after Wednesday’s IT-led slide; broad-based rally in FMCG, financials and banks; crude near six-month highs capped gains
USD / INR≈95.28Rupee weakened 21 paise on dollar strength, higher US Treasury yields and elevated crude; RBI continues to defend near 95; import-bill pressure persists
Brent Crude≈$115 (6-mo high)Crude sits near six-month highs after the Saudi refinery attack; geopolitical risk premium intact; major import-cost headwind for India; WTI elevated in tandem
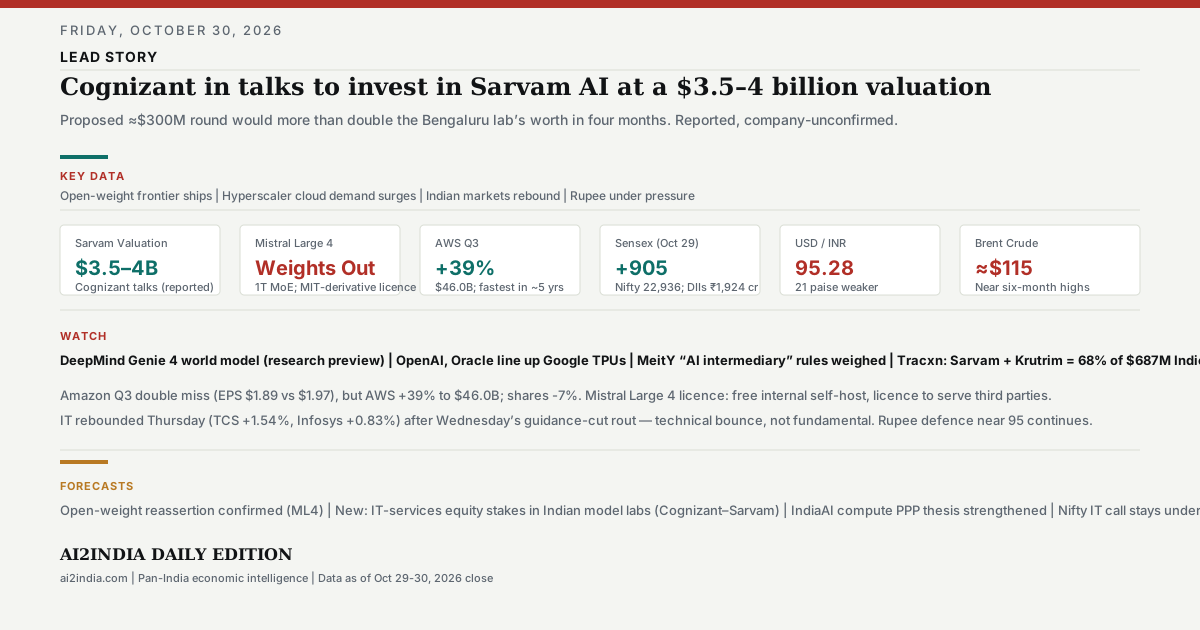
October 30, 2026 signal board: Cognizant in talks to invest in Sarvam AI at a $3.5-4 billion valuation (reported ~$300M round, four-month doubling). Mistral Large 4 Le Chonk open weights released (1T MoE, MIT-derivative license, free internal use).
Today’s economic signal board. Full analysis in the Daily Edition.
Full image description — 355 characters

October 30, 2026 signal board: Cognizant in talks to invest in Sarvam AI at a $3.5-4 billion valuation (reported ~$300M round, four-month doubling). Mistral Large 4 Le Chonk open weights released (1T MoE, MIT-derivative license, free internal use). Amazon Q3 double miss; AWS +39% to $46B. OpenAI and Oracle line up Google TPUs. Sensex +905; Nifty 22,936.

Lead Analysis

Cognizant in talks to invest in Sarvam AI at a $3.5–4 billion valuation

A proposed ≈$300 million round would more than double the Bengaluru lab’s worth in four months and hand a Nasdaq-listed IT major its first equity stake in an Indian foundation-model startup.

Friday, October 30, 2026: The Economic Times reports Cognizant is in talks to participate in Sarvam AI’s latest financing round, valuing India’s sovereign-AI flagship at $3.5–4 billion. The talks are sourced, not confirmed by either company.

ET, corroborated by Inc42 and Business Upturn, reports that Cognizant Technology Solutions is negotiating a stake in Sarvam AI as part of a proposed ≈$300 million fundraise at a $3.5–4 billion valuation — more than double Sarvam’s previous mark, and a four-month doubling. Cognizant is one of the largest IT employers in India; an equity position would be the first direct investment by a major global IT-services firm in a domestic foundation-model lab.

The context makes the number meaningful. Sarvam won the MeitY IndiaAI Mission foundational-model incentive round-one award alongside Soket Labs, Gnani.ai and Gan.ai, and signed a defence MoU with HQ IDS covering all three services. Tracxn’s new “Indic AI: Building AI for Bharat” report shows Sarvam (≈$389M) and Krutrim (≈$75M) together absorbing 68% of the $687M in tracked Indic-AI funding. Capital concentration on this scale means the round is not just a Sarvam event: it sets the benchmark every other Indian model lab will be measured against.

For Indian enterprises the signal is strategic, not just financial. IT services firms squeezed by AI-era margin compression (Infosys cut FY27 guidance last week even as AI hit 10.5% of revenue) are choosing to own model-IP rather than rent it. A Cognizant–Sarvam tie-up would create a captive enterprise channel for Indian-language and sovereign models, and it would pressure TCS, Infosys and Wipro to answer a new question: who owns the model your supplier sells you?

There are two caveats. The talks are reported, not confirmed — valuations in Indian AI rounds have moved fast this year, and terms could shift. Second, MeitY’s emerging “AI intermediary” framework, which Big Tech is lobbying to keep separate from social-media intermediary rules, will likely scrutinise exactly this kind of cross-border equity into Indian AI infrastructure.

Markets, meanwhile, staged their best session of the week. Sensex closed ≈74,151 (+905 pts), Nifty reclaimed 22,900 to ≈22,936, with FMCG and financials leading and IT rebounding (TCS +1.54%, Infosys +0.83%) after Wednesday’s sell-off. DIIs were net buyers of ₹1,924 crore. The rupee weakened 21 paise to ≈95.28 on dollar strength and crude near six-month highs. Overnight, Amazon’s Q3 double miss (AWS +39% to $46.0B, its fastest growth in nearly five years) sets up a telling contrast for Friday: cloud demand is booming while consumer and ads softness hits margins.
AI-generated illustration for: Cognizant in talks to invest in Sarvam AI at a $3.5–4 billion valuation
AI-generated illustration. Not a photograph of the events described.

AI Developments Today

Friday, October 30, 2026: Top AI stories with source, India relevance, and enterprise impact. Lead: Cognizant’s reported $3.5–4B Sarvam AI talks. Below: Mistral Large 4 open weights released (Le Chonk, 1T MoE, MIT-derivative license); Amazon Q3 double miss with AWS +39%; DeepMind Genie 4 world model; OpenAI and Oracle line up Google TPUs.

StoryKey DetailsIndia RelevanceWhat This Means for Indian EnterpriseSource / Date
Cognizant in talks to invest in Sarvam AI at $3.5–4B valuation
Proposed ≈$300M fundraise; more than double previous valuation; first global IT-services equity stake in an Indian foundation-model lab (reported)
Oct 28-29 (Economic Times exclusive; Inc42; Business Upturn; Wocult; Channeliam): Cognizant Technology Solutions (Nasdaq) negotiating participation in Sarvam AI’s latest financing round, expected to value the Bengaluru sovereign-AI startup at $3.5–4 billion — more than double its prior valuation in about four months. Round size reported at ≈$300 million. Sarvam: MeitY IndiaAI Mission foundational-model incentive winner; HQ IDS defence MoU (Oct 26); Tracxn lists Sarvam cumulative funding ≈$389M. Neither company has confirmed. Direct India signal: the flagship Indian model lab attracts a Nasdaq-listed IT major as investor. Would create an enterprise channel distributing Sarvam models into Cognizant’s client base, and sets the valuation benchmark for Krutrim, Gnani.ai, Soket Labs and the rest of the Indic-AI tier. Validates the sovereign-AI procurement thesis Indian enterprises have been weighing. (1) Map which IT-services supplier controls which model vendor; ownership changes procurement leverage. (2) If you run regulated or Indian-language workloads, Sarvam access may soon arrive pre-integrated through an enterprise channel rather than separate procurement. (3) Treat the number as directional — reported, not confirmed; watch for the formal round announcement. Reported India — ET exclusive (Tier 1/2); company-unconfirmed; Oct 28-29, 2026
Mistral Large 4 “Le Chonk” open weights released
1T-total / 49B-active MoE, 1M context, multimodal; Mistral Ecosystem Open-Weight License (MIT derivative); free internal use, licence needed to serve third parties
Oct 29 (Mistral via Hugging Face; runtimewire; DEV Community; Hacker News; Digg): Weights shipped ahead of the Oct 31 countdown in FP8 and NVFP4 variants plus community GGUFs. Architecture: sparse attention + Pixtral vision encoder; text+image in, text out. License is the headline: MIT derivative named “Mistral Ecosystem Open-Weight License” — internal use and fine-tuning free; model-as-a-service to third parties requires a licence. Cyber: 82% on the Artificial Analysis Cyber Index (reproduce-then-patch); StrongREJECT/AgentHarm refusal rate highest among open-weight models. Positioned for defensive security, coding agents and multimodality. Resolves the exact question this publication has tracked since Oct 27: the license is now known and it is permissive for self-hosting. Indian enterprises can run a frontier-class 1T MoE on their own infrastructure for internal and regulated workloads without API fees; exporting the model as a paid service to others is restricted. A sovereign-hostable frontier alternative to closed US/China APIs is now real, not pending. (1) Stand up an evaluation harness now; 49B active params is heavy for on-prem but feasible for GPU-equipped GCCs and cloud tenants (FP8/NVFP4 cut serving cost). (2) Read licence terms before any commercial resale or hosted third-party offering. (3) Defensive-security teams should test reproduce-then-patch workflows: open weights keep policy and deployment control in-house mid-incident. Verified global — Hugging Face blog; Mistral; runtimewire (Tier 1/2); Oct 29-30, 2026
Amazon Q3: double miss, AWS revenue +39% to $46.0B
EPS $1.89 vs $1.97 est; revenue $201.94B vs $202.31B; AWS operating income $17.77B (+55%, record ≈23% of revenue); 2026 capex forecast held
Oct 29 after US close (CNBC; Benzinga; ShiftDelete): Amazon reported EPS $1.89 (miss), revenue $201.94B (miss). AWS grew 39% to $46.0B — fastest pace in nearly five years — with operating income $17.77B, up 55%, now roughly 23% of Amazon revenue (record). Advertising $19.64B vs $20.82B consensus. Shares dropped more than 7% after hours. Company held its 2026 capex spending forecast, signalling sustained AI/cloud infrastructure investment. AWS +39% is the strongest hyperscaler cloud-growth data point of the quarter and a direct demand signal for Indian cloud-migration and AI-infrastructure services. But the consumer/ads miss and 7% share drop show the market is now pricing AI-cloud leadership negatively when core retail softens — the same uneven-monetisation pattern seen in Alphabet’s miss on Oct 28. (1) AWS growth supports continued cloud-services demand for Indian SIs and GCCs; capacity-constrained regions may see pricing firmness. (2) Amazon’s capex hold implies continued partner demand for data-centre and managed-infrastructure work in India. (3) Expect Indian IT names to trade with Amazon’s cloud narrative on Friday open, not just its earnings miss. Verified global — CNBC; Benzinga (Tier 1/2); Oct 29, 2026
Google DeepMind unveils Genie 4: interactive world model with sound
Real-time natural-language scene steering; research preview
Oct 27-28 (DeepMind official; AIdapted roundup): Genie 4 generates realistic interactive environments and modifies them in real time from natural-language instructions, simulating character movement, object interactions, ambient sound, music and dialogue. Research preview for a limited tester group; expected to reach users via Google services. DeepMind acknowledges long-simulation coherence limits. World models are the training substrate for robots and agents — the workloads Indian GCCs and robotics startups are beginning to build around. A generative simulation layer compresses the cost of environment creation for agent testing, autonomous-vehicle simulation and game prototyping out of Indian R&D teams. (1) Watch the preview-to-product path; agent-evaluation teams should benchmark simulated environments against real-world test harnesses before adopting. (2) Indian robotics/autonomous-systems firms should track Genie 4’s API availability as a synthetic-data option. (3) No pricing or India availability yet — treat as capability signal, not procurement option. Verified global — DeepMind official; AIdapted (Tier 1/2); Oct 27-28, 2026
TPU supply chain opens: OpenAI reportedly to buy Google TPUs; Oracle to offer TPUs on OCI
Diversification beyond NVIDIA; Oracle first major cloud outside Google with TPUs (2027) plus Cerebras inference
Oct 27-28 (Reuters via The Information; Oracle announcement; AIdapted): OpenAI reportedly plans to purchase Google TPUs to diversify beyond NVIDIA GPUs; no financial terms. Separately, Oracle announced it will add Google TPUs to Oracle Cloud Infrastructure — a first for a major cloud outside Google — with availability planned 2027, plus a Cerebras collaboration for AI inference. Reports did not constitute a confirmed contract for OpenAI. A multi-vendor accelerator market lowers India’s single-vendor GPU dependency risk over time: sovereign AI compute programmes (IndiaAI Mission, Yotta, Tata, Jio) that pool TPU, Cerebras and GPU capacity gain negotiating leverage against NVIDIA allocation queues. (1) Indian AI-infrastructure planners should re-run capacity plans with a multi-accelerator scenario; 2027 TPU-on-OCI availability is the first concrete third-party option. (2) Cloud procurement teams should ask hyperscalers for accelerator-portfolio roadmaps, not just GPU quotas. (3) For 2026, NVIDIA allocation remains the binding constraint. Verified global — Reuters; Oracle (Tier 1/2); Oct 27-28, 2026

India AI Ecosystem

Friday, October 30, 2026: Tier-4 platforms, NASSCOM signals, MeitY policy, ecosystem developments. NEW THIS CYCLE: Cognizant–Sarvam stake talks ($3.5–4B valuation, reported); Tracxn’s full Indic-AI report ($687M tracked, Sarvam+Krutrim 68%); MeitY weighs separate “AI intermediary” rules; DPDP (Removal of Difficulties) Order 2026 clarified. Carried baselines stand.

Platform / SignalUpdateSource / Date
Cognizant–Sarvam stake talks (NEW)Oct 28-29: ET exclusive — Cognizant in talks to participate in Sarvam AI’s ≈$300M round at a $3.5–4B valuation, more than double the previous mark. Reported, company-unconfirmed. If closed, first global IT-services equity stake in an Indian foundation-model lab; would extend Sarvam’s enterprise channel (MeitY IndiaAI Mission winner; HQ IDS defence MoU).Economic Times; Inc42; Business Upturn (Tier 1/2); Oct 28-29, 2026
Tracxn: Sarvam + Krutrim = 68% of tracked Indic-AI funding (NEW, full-report numbers)Oct 29: Tracxn report “Indic AI: Building AI for Bharat” tracks $687M total funding across 34 companies; Sarvam (≈$389M) and Krutrim (≈$75M) together $464M, or ~68%. Sarvam alone is ~57% of tracked capital. Supersedes the earlier 2026-only cut ($399M; Sarvam 87% of 2026 flows). Concentration, not breadth, characterises Indian model-building capital.Analytics India Mag; CIOL; Lapaas Voice citing Tracxn (Tier 2); Oct 29, 2026
MeitY: separate “AI intermediary” rules weighed (NEW)Oct 28 (Elets CIO): Lawyers and Big Tech have submitted representations and whitepapers to MeitY arguing AI platforms need an intermediary definition distinct from India’s social-media intermediary rules, ahead of the AI law/digital bill consultation round. Delimitation of liability (safe harbour) is the core contested question, with direct consequences for AI platform providers and enterprise deployers.Elets CIO (Tier 2); Oct 28, 2026
DPDP (Removal of Difficulties) Order, 2026 (NEW)MeitY order under DPDP Act Section 60 clarifies guardian consent for children / persons with disability and changes Section 10(2)(c)(ii) from “periodic audit” to “periodic data audit”. Directly affects consent architecture in AI-driven data pipelines, edtech and healthtech handling minor data.IMPRI policy update (Tier 2); Oct 29, 2026
MeitY consultation paper clock (carried, updated)Due early-mid November; safety, security, skilling pillars. The AI-intermediary representations land in this window. Expected within roughly one week.The Hindu; ThePrint; Elets CIO (Tier 2); Oct 8-28, 2026
Sarvam-HQ IDS defence MoU (carried)Oct 26: Sarvam signs MoU with HQ IDS for Army-Navy-Air Force AI framework covering operational, training and decision-support across all three services.Business Standard; Rediff (Tier 2); Oct 26-28, 2026
FT: Indian outsourcers defy AI threat -- AI work >10% of revenueOct 27: TCS and Infosys confirm AI integration work accounts for more than 10% of total revenue.Financial Times (Tier 1); Oct 27, 2026
Infosys Q2 FY27: AI 10.5% of revenue (carried)Oct 28: AI revenue 10.5% of total; +29% sequential; FY27 guidance cut; four downgrades in a day.InvestYwise; Business Standard (Tier 2); Oct 28, 2026
Krutrim leadership exodus (carried)Oct 25: ET reports leadership exodus and workforce reduction; 60+ linguistics staff and AI/semiconductor leaders departed; funding dried up. Krutrim remains #2 in Tracxn’s Indic-AI tracked funding (≈$75M).Economic Times (Tier 1); Oct 19, 22, 25, 2026
Karmayogi-OpenAI MoU (carried)Oct 21: OpenAI Academy integrated into iGOT Karmayogi platform for 1.7 crore government employees.ET; HBL; Rediff (Tier 1/2); Oct 21, 2026
NIELIT Quantum & AI University Campus, Amaravati (carried)HBL (Oct 26): Proposed entirely grant-in-aid from MeitY for NIELIT’s quantum and AI campus; CRDA meeting chaired by AP CM Chandrababu Naidu.The Hindu BusinessLine (Tier 2); Oct 26, 2026
TCS / Infosys / HCLTech AI revenue figures (carried)Nikkei Asia (Oct 26): TCS AI revenue +19%+ YoY past 10% ($3.1B annualized); Infosys AI revenue +29% QoQ ~10.5%; HCLTech advanced-AI $219M (+28.4% QoQ, +78% YoY CC).Nikkei Asia; HBL (Tier 2); Oct 26, 2026
Infosys-Truist GCC (carried)Oct 19: Infosys and Truist strengthen collaboration to build a GCC in India; Topaz expands.Infosys IR (Tier 1); Oct 19, 2026
IBM-Yotta sovereign platform (carried)Bengaluru: watsonx Orchestrate on Yotta Shakti Cloud with Studio fine-tuning.IBM-Yotta joint; Sep 29, 2026
CoRover.ai / BharatGPT (carried)Winner of Government of India agentic-AI RFP under MeitY/NeGD (Sept 30).CXO Today; ET (Tier 2); Sept 30-Oct 2026

AI Adoption Impact

Friday, October 30, 2026: Enterprise AI adoption data, AI-driven hiring/layoff signals, productivity shifts. NEW this cycle: AWS +39% growth validates hyperscale cloud-AI demand; Mistral open weights unlock a self-host adoption path; Tracxn funding concentration reshapes the vendor map. Carried lanes updated with fresh evidence.

SignalData PointSource / DateTrajectory
AWS revenue +39% to $46.0B (NEW)Fastest AWS growth in nearly five years; operating income $17.77B (+55%), a record ~23% of Amazon revenue. Hyperscaler cloud-AI demand remains the strongest data point of the quarter despite Amazon’s overall miss (EPS $1.89 vs $1.97; revenue miss; ads $19.64B vs $20.82B).CNBC; Benzinga (Tier 1/2); Oct 29, 2026Accelerating cloud-AI demand
Mistral Large 4 self-host path opens (NEW)1T-total/49B-active MoE released under MIT-derivative licence: free internal use and fine-tuning; licence required to serve third parties. Cyber index 82% (reproduce-then-patch). Open-weight frontier is now deployable inside Indian regulated estates without per-token fees — with a resale restriction.Hugging Face; Mistral; runtimewire (Tier 1/2); Oct 29-30, 2026New adoption pathway
Indic-AI capital concentration (NEW)Tracxn: $687M tracked across 34 Indic-AI companies; Sarvam ($389M) + Krutrim ($75M) = 68%. Late-stage rounds (Cognizant–Sarvam talks at $3.5–4B) now dominate over early-stage spread.Analytics India Mag; CIOL (Tier 2); Oct 29, 2026Consolidating vendor map
52% of Indian CEOs plan workforce cuts as AI reshapes hiring (carried)PwC survey of 125 Indian CEOs (Aug 11-Sept 21, 2026): 52% plan AI-driven workforce reductions; 87% focus on retaining/retraining high-potential employees.PwC via BusinessToday (Tier 2); Oct 28, 2026Structural; planning stage
Innodata ~550 India layoffs (carried, date confirmed)US data/AI services firm cut ~550 India roles on Oct 26 with additional cuts in the Philippines; laptop access shut before termination emails; letter cited ramp-down. Delhi engineer among affected.NDTV; CIOL; Inc42 (Tier 2); Oct 26-29, 2026AI-services rationalisation
Global tech layoffs YTD 2026 (carried)Layoffs.fyi: 135,446 tech workers across 333 companies as of Oct 28 (~450/day). Aggregate; no India split.Layoffs.fyi (Tier 2); Oct 28, 2026Continuing structural decline
Xpheno six majors net -24K headcount (carried)TCS, Infosys, HCLTech, Wipro, TechM, LTIMindtree combined 822,144 → 797,722 (Oct 2025-26); ~92K exits vs ~68K intake.Xpheno via ET (Tier 2); Oct 23, 2026Confirmed downward
GCC hiring caution (carried)Avg headcount per India GCC stalls near 1,115; ~65% of new GCC roles require AI skills (ANSR).ANSR; Outsource Accelerator (Tier 2); Oct 20-24, 2026Structural shift
LLM price collapse (carried, ML4 updated)Luna $0.20/$1.20; Terra $1/$5; Sonnet 5 $2/$10; Gemini 4 Carbon $2/$10 intro; Mistral Large 4: open weights (free internal self-host) with API preview cited ~$4.18/M output; serving third parties requires licence.Vendor pricing; minimaxir.com (Tier 1/2); Jun-Oct 2026Floor expanding; self-host option new

Five Things That Changed

Friday, October 30, 2026: 3 AI items, 1 AI-economy item, 1 policy item — each with verified data and source.

SignalData PointReader ImpactStatus
1. Cognizant in talks to invest in Sarvam AI at $3.5–4B (Economic Times; Inc42; Business Upturn, Oct 28-29): Proposed ≈$300M fundraise; valuation more than doubles in four months. First global IT-services equity stake in an Indian foundation-model lab. Sarvam: IndiaAI Mission incentive winner; HQ IDS defence MoU; ≈$389M cumulative tracked funding (Tracxn). Reported, company-unconfirmed. If it closes, sovereign-AI capital gets an enterprise distribution arm: Sarvam models could reach Cognizant’s client base pre-integrated, and the $3.5–4B mark resets every Indic-AI benchmark for Krutrim and the rest. For IT services, it is a hedge against the margin compression Infosys disclosed last week (AI 10.5% of revenue, guidance cut). Re-map supplier ownership: which IT vendor controls which model vendor is now a procurement question. Regulated-workload buyers should track Sarvam’s enterprise channel plans. Reported India — ET exclusive (Tier 1/2); company-unconfirmed; Oct 28-29, 2026
2. Mistral Large 4 “Le Chonk” open weights released (Hugging Face; Mistral; runtimewire, Oct 29-30): 1T-total/49B-active MoE, 1M context, multimodal; FP8 + NVFP4 + community GGUFs. Mistral Ecosystem Open-Weight License (MIT derivative): free internal use and fine-tuning; model-as-a-service to third parties requires licence. 82% on AA Cyber Index (reproduce-then-patch). The license question this publication tracked since Oct 27 is resolved: self-hosting a frontier-scale open model inside India is now permitted without per-token fees, with a resale restriction. Defensive-security teams gain a model whose usage policy and deployment stay under their control mid-incident. Stand up an evaluation harness now; read licence terms before any commercial hosting. GPU-equipped GCCs and cloud tenants are the natural first deployers. Verified global — Hugging Face blog; Mistral (Tier 1/2); Oct 29-30, 2026
3. Amazon Q3 double miss with AWS +39% (CNBC; Benzinga, Oct 29): EPS $1.89 vs $1.97 est; revenue $201.94B vs $202.31B; AWS $46.0B (+39%, fastest in ~5 years), op income $17.77B (+55%, record ~23% of revenue); ads $19.64B vs $20.82B; shares -7%+ after hours; 2026 capex forecast held. Hyperscaler cloud-AI demand is booming while non-cloud monetisation (consumer, ads) disappoints — the same uneven-payoff pattern Alphabet showed on Oct 28. Amazon holding capex signals continued infrastructure spend into 2027, a positive for cloud-services demand that Indian SIs and GCCs serve. Cloud-services demand reads positive; expect Indian IT to trade with the AWS narrative Friday. Capacity-constrained regions may see pricing firmness. Verified global — CNBC; Benzinga (Tier 1/2); Oct 29, 2026
4. Markets rebound: Sensex +905 to ≈74,151; Nifty 22,936 (Moneycontrol; TOI; HBL, Oct 29): Reclaimed 22,900; FMCG and financials led; Adani Ports, Kotak Bank top gainers; IT rebounded (TCS +1.54% to ₹2,498, Infosys +0.83%). DIIs net buyers ₹1,924 crore (cash). Rupee -21 paise to ≈95.28; crude near six-month highs. The rebound unwound Wednesday’s IT-led slide without new AI fundamentals: IT bounced on short-covering after Infosys’ guidance cut. DII buying at ₹1,924 crore against a weakening rupee is a domestic-liquidity offset, but crude near six-month highs and a pending Fed hike keep the macro overhang. Treat Thursday’s IT bounce as technical, not a margin-recovery signal. Rupee 95.28 pressure continues to favour USD-earning exporters’ coverage planning. Verified India — Moneycontrol; TOI; HBL (Tier 2); Oct 29, 2026
5. MeitY AI-law groundwork: “AI intermediary” definition + DPDP order (Elets CIO; IMPRI, Oct 28-29): Big Tech representations argue AI platforms need safe-harbour rules distinct from social-media intermediary rules ahead of the consultation paper (due early-mid Nov). MeitY also issued DPDP (Removal of Difficulties) Order 2026 (Sec 60): guardian-consent clarification for children / persons with disability; “periodic audit” → “periodic data audit” in S10(2)(c)(ii). Two signs India’s AI rulebook is taking shape before year-end: platform-liability delimitation and data-audit clarity. The intermediary decision will set safe-harbour obligations for every AI platform selling into India; the DPDP order tightens consent and audit compliance for AI data pipelines handling minors. AI platform providers and data-heavy deployers should model both regimes: intermediary-liability drafting and periodic data-audit obligations before the consultation window closes. Verified India — Elets CIO; IMPRI (Tier 2); Oct 28-29, 2026

Data Variables Ledger

Friday, October 30, 2026: Key numbers for AI and economy trackers. Updated with verified data from Oct 29-30. Markets reflect October 29 close.

VariableCurrent ValuePrior ValueChangeSource / Date
Cognizant–Sarvam round (NEW)Reported: Cognizant in talks to invest in Sarvam AI at $3.5–4B valuation; ≈$300M fundraise; more than double prior mark in ~4 months. Company-unconfirmed.Sarvam ≈$389M cumulative tracked funding (Tracxn)First global IT-services stake in Indian foundation-model lab; resets Indic-AI valuations.Economic Times; Inc42; Business Upturn (Tier 1/2); Oct 28-29, 2026
Mistral Large 4 (RESOLVED)Weights released Oct 29 (Le Chonk): 1T total/49B active MoE, 1M context, multimodal; FP8/NVFP4 + GGUF. Mistral Ecosystem Open-Weight License (MIT derivative): free internal use; licence to serve third parties. AA Cyber Index 82%.Countdown to Oct 31; license HTTP 404License question resolved; sovereign self-host path open.Hugging Face; Mistral (Tier 1); Oct 29-30, 2026
Amazon Q3 (NEW)EPS $1.89 (miss vs $1.97); revenue $201.94B (miss vs $202.31B); AWS $46.0B +39% (fastest in ~5 yrs); AWS op income $17.77B +55% (record ~23% of revenue); ads $19.64B vs $20.82B; shares -7%+; capex forecast held.N/ACloud-AI demand booming; consumer/ads soft; uneven monetisation continues.CNBC; Benzinga (Tier 1/2); Oct 29, 2026
Sensex (UPDATED)≈74,151 (Oct 29; ↑905 pts, ↑≈1.2%)73,246.03 (Oct 28; -0.48%)Sharp rebound; FMCG/financials led; IT bounced (TCS +1.54%, Infosys +0.83%).Moneycontrol; TOI; HBL (Tier 2); Oct 29, 2026
Nifty 50 (UPDATED)≈22,936 (Oct 29; ↑≈237 pts, ↑≈1.0%)22,698.85 (Oct 28; -0.22%)Reclaimed 22,900; Adani Ports, Kotak Bank top gainers.Moneycontrol; TOI (Tier 2); Oct 29, 2026
USD / INR (UPDATED)≈95.28 (Oct 29)95.23 (Oct 28)Weakened 21 paise; dollar strength + higher US yields + elevated crude; RBI defending near 95.Hindu BusinessLine (Tier 2); Oct 29, 2026
Brent Crude (UPDATED)≈$115, near six-month highs (Oct 29)≈$115+ (Oct 28)Hold near six-month highs; geopolitical risk after Saudi refinery attack.NDTV; HBL (Tier 2); Oct 29, 2026
DII cash flows (NEW)DIIs net buyers ₹1,924.40 cr (Oct 29, cash segment provisional).Oct 28: DIIs net buyers ₹643 crDomestic liquidity strongly supporting the rebound.5paisa (Tier 2); Oct 29, 2026
Indic-AI funding (UPDATED)Tracxn: $687M tracked across 34 companies; Sarvam ≈$389M + Krutrim ≈$75M = $464M (68%).Earlier 2026-only cut: $399M, Sarvam 87%.Full-report numbers supersede; concentration confirmed.Tracxn via Analytics India Mag; CIOL (Tier 2); Oct 29, 2026
Gemini 4 Carbon (carried)#1 on AA Intelligence Index v5.0 (59); intro $2/$10, permanent $4/$20; cyber focus; US gov review gate.N/AUnchanged.Google blog; 9to5Google (Tier 1/2); Oct 28, 2026
ETH disproof (carried)OpenAI + Anthropic confirm AI-derived disproof of Exponential Time Hypothesis; Lean-verified; algorithm 2^(n/sqrt(log n)) for 3-SAT; no P=NP proof; no direct crypto threat.N/AUnchanged.OpenAI; TechCrunch; Ars Technica (Tier 1/2); Oct 26-28, 2026
Infosys Q2 FY27 (carried)Rev +1.2% YoY CC; AI 10.5% of revenue (+29% seq); FY27 guidance cut; 4 downgrades; stock -4.26% (Oct 28); +0.83% rebound (Oct 29).Oct 28 closeCarried; stock stabilised Thursday.Business Standard; InvestYwise (Tier 1/2); Oct 28-29, 2026
Kimi K3.1 Pro weights (carried)Planned Nov 4 (AA Index 55, 4th overall, 1M context).UnchangedUnchanged.Moonshot; CGTN (Tier 1/2); Oct 23, 2026
Repo rate (carried)5.50% (RBI); Fed held 3.75-4.00% (Oct 28, 10-2; Dec hike expected).UnchangedFed overlay unchanged.RBI; The Street (Tier 1/2); Oct 7-29, 2026

Verified Layoff Radar

Friday, October 30, 2026: India-confirmed only. AI-driven restructuring flagged separately. No new India-specific layoff events this cycle; Innodata date/source detail updated (Oct 26 action, Philippines also affected). Carried rows stand.

CompanyIndia ImpactDriverSource / DateStatus
Innodata ~550 laid off (UPDATED detail)US data/AI services firm cut ~550 India roles on Oct 26 (laptop access shut before termination email; letter cited ramp-down); additional reductions in the Philippines. Delhi-based engineer among affected. India-specific official count undisclosed.AI-services industry rationalisation (data preprocessing/annotation workflows) + ramp-down cited in letterNDTV; CIOL; Inc42; Lapaas Voice (Tier 2); Oct 26-29, 2026Reported India — Delhi engineer confirmed; company-undisclosed India split
52% of Indian CEOs plan workforce cuts (carried signal)PwC survey of 125 Indian CEOs (Aug 11-Sept 21, 2026): 52% plan AI-driven workforce reductions; 87% prioritise retaining/retraining high-potential employees. Planning stage, not execution.AI-driven restructuring planning across sectorsPwC via BusinessToday (Tier 2); Oct 28, 2026Signal — planned, not executed
Microsoft 60K voluntary buyouts (carried)India explicitly eligible; no India headcount disclosed; voluntary; participation unknown.AI-era workforce restructuring + capital efficiencyCNBC; Bloomberg; NYT (Tier 1); Oct 26, 2026Verified global — India eligible; no India count
India GCCs -- aggregate estimate (carried)ThePrint: ~4,000-5,000 GCC layoffs estimated in India 2026 as AI reshapes team structures; avg headcount per GCC stalls near 1,115. Industry estimate.AI adoption + right-sizing GCC footprintsThePrint (Tier 2); ANSR; Outsource Accelerator; Oct 20-24, 2026Reported India — estimate, no company split
Krutrim workforce reduction (carried)Over 60 linguistics staff + AI/semiconductor leaders departed; funding dried up; plans shrinking.Funding contraction + product demand weaknessEconomic Times (Tier 1); Oct 19, 22, 25, 2026Reported India — confirmed by ET
Six IT majors net -24K headcount (carried)Xpheno: combined 822,144 → 797,722; ~92K exits vs ~68K intake (Oct 2025-26).AI adoption + bench managementXpheno via ET (Tier 2); Oct 23, 2026Verified India — net attrition
Top-5 IT Q2 results (carried)Infosys FY27 guidance cut; TechM +32.7%; Wipro -1.4%; TCS +15% PAT; HCLTech +21.2%. AI share expanding, margins compressing.AI-augmented delivery; demand rebalancingLivemint; Nikkei Asia; FT (Tier 1/2); Oct 28, 2026Verified India — mixed; Infosys guidance cut
Oracle India (carried)≈3,000 employees potentially affected; India split company-undisclosed.AI/cloud-infrastructure redirectTimes Now; Fortune India; Sep 2026Reported India — company-undisclosed
US PERM suspension (carried)TCS, Infosys, Wipro, HCLTech, Cognizant, Capgemini, Microsoft, Adobe barred Oct 8. Pending frozen.US labour-policy actionTOI; Indian Express; Hindu (Tier 1/2); Oct 8-10, 2026Verified India relevance — no headcount impact
Indian IT structural shift (carried)FY26 net reduction ~7K (top-5) vs +12.7K FY25; campus hiring at two-decade low.AI-augmented delivery + precision hiringTeamLease; Naukri; Xpheno (Tier 2); Oct 1-23, 2026Verified India — structural shift

Hiring Demand Watch

Friday, October 30, 2026: AI/cloud/cybersecurity roles vs general IT focus. NEW this cycle: Mistral open-weights release lifts self-host inference and security-ML demand; Sarvam scale-up hiring contingent on round close. Carried lanes stand.

SegmentSignalData PointSource / Date
Self-host / open-weight inference roles (NEW)Mistral Large 4 release creates immediate demand for open-model deployment skills1T-total/49B-active MoE with FP8/NVFP4 serving paths — teams able to stand up, quantise and fine-tune open weights (vLLM, llama.cpp, TRL) inside regulated estates are the scarce hire this week. Defensive-security reproduce-then-patch workflows add security-ML demand.Hugging Face; DEV Community (Tier 1/2); Oct 29-30, 2026
Sarvam scale-up hiring (NEW signal)Round-dependent headcount expansionProposed ≈$300M round at $3.5–4B (reported) would fund compute and team expansion across Indic-language model R&D, defence-AI and enterprise deployment. Hiring materially contingent on close; watch for post-announcement openings.Economic Times; Inc42 (Tier 1/2); Oct 28-29, 2026
52% CEOs plan cuts; 87% retain top talent (carried)Dual signal: planned reductions, high-potential retentionPwC 125-CEO survey: 52% plan AI-driven workforce cuts; 87% retain/retrain high-potential staff.PwC via BusinessToday (Tier 2); Oct 28, 2026
GCC AI-skills demand quantified (carried)65% of new roles need AI skillsANSR: nearly 65% of new GCC roles in India 2026 require AI skills; avg headcount per centre near 1,115.ANSR (Tier 2); Oct 23-24, 2026
Microsoft buyouts releasing mid-level talent (carried)60K voluntary exits, India included, level ⌚70Voluntary exits at level 70 and below may release experienced Azure/Copilot engineers into the market.CNBC; Bloomberg; NYT (Tier 1); Oct 26, 2026
Krutrim workforce release (carried)60+ linguistics/LLM specialists exit marketSpecialists trained on Indian languages and multimodal pipelines available to GCCs building Hindi/Tamil/Telugu/Marathi capability.Economic Times (Tier 1); Oct 19-25, 2026
Formal-verification talent (carried)ETH disproof validates formal methodsOpenAI + Anthropic used Lean for machine-checked proofs; frontier labs treat formal verification as core. Scarcity and premium pricing expected for Lean/Coq skills.OpenAI; TechCrunch (Tier 1/2); Oct 26-28, 2026
NASSCOM/Taggd AI deficit (carried)AI demand +300% vs 2024; 53% skill deficitDecoding Jobs 2026: AI talent demand +300%+ vs 2024; 53% AI skill deficit.NASSCOM/Taggd (Tier 2); Oct 24, 2026
AI/ML hiring vs white-collar market (carried)Naukri JobSpeak SeptemberWhite-collar +2% YoY; AI/ML +20% YoY (record); IT-services recruitment subdued.ET; ANI (Tier 2); Oct 2-3, 2026
DPDP compliance roles (carried)NASSCOM x MeitY workshops16-city DPDP implementation workshops through Jan 2027; DPDP leads, privacy engineers; new Removal-of-Difficulties order sharpens audit obligations.NASSCOM; IMPRI (Tier 2); Oct 7-29, 2026

Real Estate Pulse

Friday, October 30, 2026: GCC and AI-company office moves. No new India real estate events this cycle. Carried rows stand.

Company / ProjectLocationDetailStatus
TCS Hyderabad data-centre project (carried)Hyderabad₹70,000 crore DC project announced Q2 -- largest single AI-infrastructure commitment.Verified India — TCS; Oct 8-9, 2026
Microsoft Hyderabad region (carried)HyderabadLaunched Sept 21; three availability zones; zero-water cooling; AI-workload focus.Verified India — Sept 21, 2026
GCC space demand (carried)Top 7 citiesGCCs leased 19.2M sq ft in H1 2026 (45% of gross); Anarock sees 8-12M sq ft expansion; Zinnov-NASSCOM: 2,117 GCCs / 2.36M professionals.Verified India — ANAROCK; Zinnov; Oct 2026
Shillong Tech Park-II (carried)ShillongStaffFlex, Shamrock AI, Alorica, AI Centre of Excellence under IndiaAI Mission.Verified India — Highland Post; Sept 24, 2026
IndiaAI CoE Bhubaneswar (carried)BhubaneswarBlue Cloud Softech Industry Partner; ₹4 cr investment.Verified India — Business Standard; Sept 15, 2026
HCLTech Odisha AI DC + Tech Hub (carried)Bhubaneswar$1.48B AI DC with Sarvam; 5,000-seat hub; 6,000 jobs.Verified India — Reuters; Jul 2026
Infosys-Truist GCC (carried)IndiaInfosys and Truist announce strategic collaboration to build a GCC in India.Verified India — Infosys (Tier 1); Oct 19, 2026
Telangana Green Skills & Applied AI CoE (carried)HyderabadCentre opened with Microsoft, 1M1B, MeitY Startup Hub.Verified India — Careerindia (Tier 2); Oct 24, 2026

Market Signals

Friday, October 30, 2026: Brief context only — Sensex, Nifty, INR, crude as 4 ticker cards. Oct 29 close: Sensex +905, Nifty above 22,900, DIIs ₹1,924 cr net buyers, rupee 95.28, crude near six-month highs.

Nifty 50↑≈1.0%≈22,936 (Oct 29 close; ↑≈237 pts); reclaimed 22,900; FMCG/financials led; IT bounced (TCS +1.54%, Infosys +0.83%)
Sensex↑905 pts≈74,151 (Oct 29 close; ↑≈1.2%); broad rebound after Wednesday’s IT-led slide; Adani Ports, Kotak Bank top gainers
USD / INR≈95.28Rupee weakened 21 paise on dollar strength, higher US Treasury yields and elevated crude; RBI defending near 95; import-bill pressure persists
Brent Crude≈$115Near six-month highs after Saudi refinery attack; geopolitical risk premium intact; WTI elevated; a direct headwind for India’s import bill and inflation

Indian markets posted their best session of the week Thursday, with the Sensex adding 905 points to ≈74,151 and the Nifty reclaiming 22,900 to ≈22,936, led by FMCG and financials. The move unwound Wednesday’s IT-led slide largely on short-covering: TCS (+1.54% to ₹2,498) and Infosys (+0.83%) stabilised after the guidance-cut rout, but nothing in the AI-services fundamentals changed overnight. DIIs were net buyers of ₹1,924 crore, providing the domestic liquidity offset, while the rupee weakened 21 paise to ≈95.28 and crude held near six-month highs at ≈$115. Overnight after US close, Amazon delivered a Q3 double miss (EPS $1.89 vs $1.97; revenue $201.94B vs $202.31B) even as AWS grew 39% to $46.0B with record operating income — shares fell more than 7%. The AWS print is the bullish cloud-AI data point for Indian SIs and GCCs; the share reaction is the market’s verdict on uneven hyperscaler monetisation after Alphabet’s miss earlier in the week. Friday’s session opens into that tension, with crude and the Fed’s December-hike path the standing macro overhang.

Forecast Tracker Updates

Friday, October 30, 2026: Open-weight forecast confirmed with Mistral Large 4 release; new forecast added — IT-services equity stakes in Indian model labs (Cognizant–Sarvam); IndiaAI compute thesis strengthened; INR and Nifty IT calls carried with new evidence. No deleted forecasts.

All carried forecasts from Oct 29 edition retained with status adjustments shown below.

ForecastStatusConfidenceLatest Evidence (Oct 29-30)
IT services majors take equity stakes in Indian foundation-model labs (NEW)Active -- Cognizant–Sarvam talks at $3.5–4B (reported) open the laneMed-HighOct 28-29: ET reports Cognizant in talks to invest in Sarvam AI at a $3.5–4B valuation (≈$300M round). A services major buying model-IP equity, rather than renting API access, would change procurement leverage across Indian enterprise AI. If TCS/Infosys/Wipro follow to preserve channel control, expect one or two comparable stake announcements within two quarters.
Open-weight frontier reasserts outside US-China axis (CONFIRMED)Confirmed -- Mistral Large 4 weights released Oct 29; licence MIT-derivative; K3.1 Pro weights due Nov 4HighOct 29-30: Mistral Large 4 (Le Chonk) shipped: 1T-total/49B-active MoE, 1M context, 82% AA Cyber Index, under the Mistral Ecosystem Open-Weight License (free internal use; licence for third-party serving). Sovereign self-host path for Indian regulated estates is now real. Kimi K3.1 Pro weights remain scheduled Nov 4 (AA Index 55).
IndiaAI Mission compute becomes PPP-served market (STRENGTHENED)Strengthened -- Sarvam capital event + multi-accelerator (TPU) supply openingMedium-HighOct 28-29: Reported $3.5–4B Sarvam round (Cognizant lead interest) funds domestic model-building/compute demand. Oracle to offer Google TPUs on OCI (2027) and OpenAI reportedly buying TPUs diversify the accelerator market that Indian PPP compute pools draw on. Tracxn: Sarvam+Krutrim 68% of $687M tracked Indic-AI funding.
Frontier API pricing floor set by open-weight + secondary inference providers (CARRIED)Confirmed -- ML4 adds a free-internal self-host option below all API tiersHighOct 29: Mistral Large 4 internal self-host costs inference hardware, not per-token fees; third-party serving requires licence. Effectively two pricing regimes now: per-token API (Terra $1/$5, Sonnet 5 and Gemini Carbon $2/$10) and hardware-cost self-host for open weights.
Compute financing concentration creates threshold effect (CARRIED)Steady -- Amazon holds 2026 capex; Fed December hike still expectedHighOct 29: Amazon held its 2026 capex forecast despite the miss, signalling sustained AI-infrastructure spend; AWS op income +55% shows monetisation improving. Fed December-hike path raises cost of GPU-infrastructure finance; CoreWeave CDS remained elevated (>10%).
Big-Tech AI-era workforce retooling accelerates (CARRIED)Active -- Meta 15% cut + Microsoft 60K buyouts + PwC 52% Indian CEOs planning cutsMed-HighNo change since Oct 28-29; PwC planning-stage data and Innodata’s Oct 26 India cuts remain the freshest signals. Watch for execution announcements through November.
Custom inference and caching reshape API cost curve (CARRIED)Active -- Gemini 4 Carbon 95%-off cache reads lead the tierHighUnchanged. Cache-read discounts (Carbon 95%, Terra $0.05, Luna $0.02) remain the dominant cost lever for high-volume Indian workloads.
Enterprise agent platforms consolidate around 2-3 universal agents (NEUTRALIZED)Weakened -- release cadence (Carbon, Genie 4, ML4) keeps acceleratingMed-LowOct 27-29: Genie 4 world model and Mistral Large 4 both land within a week of Gemini 4 Carbon. Specialisation (world sim, cyber, coding) argues for multi-model routing, not consolidation.
Multi-model access becomes cloud-agnostic procurement default (CONFIRMED)Confirmed -- open-weight self-host now a third procurement laneHighOct 29: ML4 adds self-host to the API mix (Terra/Sonnet/Carbon). Indian enterprise planners can now route by workload across three lanes: closed API, open-weight self-host, and sovereign-lab models (Sarvam).
US enters an AI enforcement era (CARRIED)Accelerated -- Gemini Carbon US-review gate; MeitY intermediary debate mirrors itHighOct 28-29: Google’s Carbon remains gated by US government review; in India, MeitY’s AI-intermediary safe-harbour debate signals a parallel rulemaking track ahead of the consultation paper.
INR depreciates to 97+ on crude > $85 (WEAKENED -- contradicted again)Contradicted -- INR 95.28 despite crude near six-month highs; RBI defending near 95LowOct 29: Rupee 95.28 (21 paise weaker) while Brent holds ≈$115. RBI intervention and DII inflows (₹1,924 cr) continue to cap the slide. Fed December hike adds USD pressure; 97+ call remains untested.
Nifty IT outperforms Nifty 50 in FY27 (UNDER PRESSURE)Under pressure -- Thursday’s IT bounce is technical, not fundamentalLowOct 29: IT rebounded (TCS +1.54%, Infosys +0.83%) after Wednesday’s -2% Nifty IT day, but on short-covering; Infosys guidance cut still stands with four downgrades. Amazon’s cloud-heavy report offers partial support via AWS demand read-through.
Repo cycle: 5.50%, calibrated tightening (CARRIED)Stable domestically; Fed December hike narrows RBI flexibilityHighUnchanged. Crude at six-month highs feeds imported inflation; watch November CPI for RBI stance.
AI hiring share of IT vacancies >15% by H2 FY27 (CARRIED)On track -- open-weight deployment roles add a new hiring laneHighOct 29-30: ML4 release adds immediate demand for self-host inference/quantisation engineers and security-ML skills; Sarvam round (reported) would add model-R&D roles if closed. ANSR 65% AI-skills requirement and Naukri AI/ML +20% YoY keep the track.

Source Notes

Friday, October 30, 2026: All cited sources, sorted chronologically by date, with source tier classification. Only sources used in this edition. No fabricated citations.

#SourceDate RangeTierSections Used In
1Economic Times (exclusive, sources): Cognizant in talks to invest in Indian AI startup Sarvam, valuing it at $3.5–4 billion; ET EnterpriseAI republication; Inc42 (proposed ≈$300M fundraise); Business Upturn; Wocult; Channeliam corroborations. Company-unconfirmed.Oct 28-29, 2026Tier 1/2Lead; AI Dev #1; Ecosystem; Five Things; Data; Forecast
2Hugging Face blog “Welcome Le Chonk: Mistral Large 4”; Mistral official collection; runtimewire; DEV Community; Hacker News discussion: 1T-total/49B-active MoE, 1M context, Pixtral vision encoder, FP8/NVFP4 + GGUF variants, Mistral Ecosystem Open-Weight License (MIT derivative; free internal use; licence for MaaS), AA Cyber Index 82% reproduce-then-patch, top open-weight refusal rates.Oct 29-30, 2026Tier 1/2AI Dev #2; Adoption; Five Things; Data; Forecast; Hiring
3CNBC (AWS Q3 + Amazon Q3 earnings reports); Benzinga; ShiftDelete.net; Tickeron: EPS $1.89 vs $1.97 est; revenue $201.94B vs $202.31B; AWS $46.0B +39% (fastest in ~5 years); AWS op income $17.77B +55% (~23% of revenue, record); ads $19.64B vs $20.82B; shares -7%+; 2026 capex held.Oct 29-30, 2026Tier 1/2AI Dev #3; Adoption; Five Things; Data; Market Signals; Forecast
4NDTV; The Times of India; Moneycontrol; Hindu BusinessLine; HDFC Sky: Oct 29 close -- Sensex ≈74,151 (+905 pts), Nifty ≈22,936 (reclaimed 22,900); FMCG/financials led; Adani Ports, Kotak Bank top gainers; TCS +1.54% (₹2,498), Infosys +0.83%; rupee -21 paise to ≈95.28; crude near six-month highs.Oct 29, 2026Tier 2Market Strip; Lead; Five Things; Data; Market Signals
5Analytics India Mag; CIOL; Lapaas Voice citing Tracxn “Indic AI: Building AI for Bharat”: $687M tracked funding across 34 companies; Sarvam ≈$389M + Krutrim ≈$75M = $464M (68%). Earlier 2026-only cut ($399M; Sarvam 87%) carried from Oct 28 edition.Oct 29, 2026Tier 2Ecosystem; Adoption; Data; Forecast
6Elets CIO: MeitY weighs separate “AI intermediary” definition and rules; Big Tech and lawyer representations submitted ahead of AI law consultation.Oct 28, 2026Tier 2Ecosystem; Five Things
7IMPRI policy update: DPDP (Removal of Difficulties) Order, 2026 (MeitY, Sec 60) -- guardian-consent clarification; “periodic audit” → “periodic data audit” in S10(2)(c)(ii).Oct 29, 2026Tier 2Ecosystem; Five Things; Hiring
8Reuters (via The Information); Oracle announcement; AIdapted roundup: OpenAI reportedly to buy Google TPUs (no confirmed contract); Oracle to add Google TPUs to OCI (2027) + Cerebras inference collaboration.Oct 27-28, 2026Tier 1/2AI Dev #5; Forecast
9DeepMind official blog (Genie 4): interactive world model with sound and real-time natural-language steering; research preview; simulations for robot/agent training; coherence limits acknowledged.Oct 27-28, 2026Tier 1AI Dev #4; Forecast
105paisa FII/DII data: DIIs net buyers ₹1,924.40 cr in cash segment on Oct 29 (provisional).Oct 29, 2026Tier 2Data; Market Signals
11NDTV; CIOL; Inc42; Lapaas Voice; OffCampusJobs4u: Innodata ~550 India layoffs on Oct 26 (laptop access shut pre-notice; letter cited ramp-down; additional Philippines cuts; Delhi engineer affected).Oct 26-29, 2026Tier 2Layoff Radar; Adoption; Hiring
12Carried unchanged from Oct 29: PwC 52% CEO survey; Microsoft 60K buyouts; Anthropic S-1; Kimi K3.1 Pro weights Nov 4; Krutrim exodus; Xpheno -24K; GCC 1,115 avg; ANSR 65% AI skills; NASSCOM +300%; Naukri AI/ML +20%; Oracle India; US PERM; Repo 5.50%; Sarvam-HQ IDS MoU; FT Indian IT >10% AI revenue; Infosys Q2; TCS/Infosys/HCL AI revenue; NIELIT Amaravati; Karmayogi-OpenAI; IBM-Yotta; CoRover; DPDP workshops; Layoffs.fyi 135,446 YTD; CoreWeave CDS >10%; Gemini 4 Carbon; ETH disproof; Fed 3.75-4.00% Dec-hike path; Brent $115+.Oct 2026Tier 1/2/3All sections; extensive carried baseline